01 Market
How many Medicare Advantage plans are there for 2027?
5,558, down 34. A small drop hiding a big mix shift: 28 states and DC lost plans, and PPOs gave way to HMOs.
Our count of unique plans, from our 2027 landscape file analysis. CMS’s own summary counts about 5,532 using a different definition.
So what: managed networks are replacing open access, so network strength carries more weight in every 2027 sale.
02 Payers
Which payers are growing in 2027, and which are pulling back?
Size didn’t decide direction. A challenger expanded fast, the biggest nationals held, and several payers cut deep.
Expanding
Devoted +313 plans
Up 73%, into 342 new counties with no exits. SCAN and Alignment also grew.
Holding steady
UnitedHealth +6 · CVS +12 · Humana −26
Humana’s lead over UnitedHealth shrank from 41 plans to 9.
Pulling back
Centene −93 · HCSC −83 · Molina −40
Each cut 29% to 48% of its plans.
So what: Devoted is now top three by plan count in Texas, Florida and Pennsylvania. Healthcare Dive found the same split: Devoted and Alignment adding counties while most large payers cut.
03 Footprint
Where did payers exit counties for 2027?
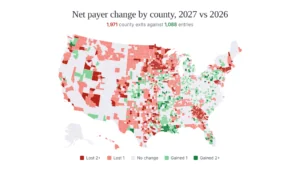
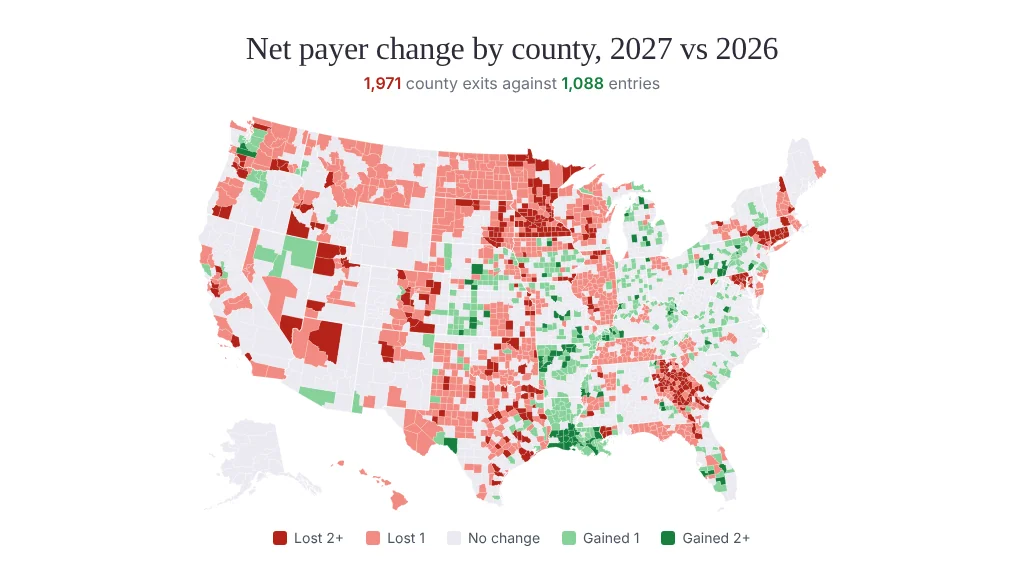
Payers left nearly twice as many counties as they entered, and each national pulled back somewhere different.
Iowa 39 · Nebraska 28 · Texas 28
South Dakota 24 · Colorado 16 · Nebraska 13
Minnesota 35 · Idaho 7 · Nebraska 6
Minnesota 12 · Nebraska 4 · California 3
A payer counts as present if it offers any plan in a county, special needs plans included. On general-enrollment plans alone, UnitedHealth exited 148 counties.
So what: members of the exiting payers’ plans must choose again this AEP. That is where share moves first.
04 Special needs plans
Are special needs plans growing in 2027?
Chronic care plans surged as dual plans dipped. D-SNPs slipped 3% in the first year of CMS’s new D-SNP enrollment limits. Devoted alone runs 255 C-SNPs, more than UnitedHealth and Humana combined.
So what: payers are trading general products for condition-specific ones. Benefit design is now a chronic care decision.
| Plan type | 2026 | 2027 | Change |
|---|---|---|---|
| C-SNP | 556 | 754 | +35.6% |
| D-SNP | 1,085 | 1,052 | −3.0% |
| I-SNP | 156 | 163 | +4.5% |
| Non-SNP | 3,795 | 3,589 | −5.4% |
05 Benefits
Which supplemental benefits are plans cutting for 2027?
The core is locked in. The extras are where plans cut. In the 2027 PBP files, dental, vision and hearing barely moved, while meals, rides and in-home support fell. Where benefits stayed, analysts found allowances tightened.
So what: when nearly every plan has dental, vision and hearing, they stop setting you apart. Targeted benefits are where 2027 plans differ.
Fewer plans offering it
More plans offering it
06 Part D
What is happening to Part D drug deductibles in 2027?
The $0 drug deductible is disappearing. 450 plans still offer one, down from 2,940 in 2023, as the standard Part D deductible rose to $700.
So what: members moving off a $0 plan, or onto a $700 one, will feel it at the pharmacy counter in January.
Humana (504) and CVS (409) have the most plans at $700; Kaiser (80) and Elevance (73) the most at $0.
07 States
What changed in the largest Medicare Advantage states?
The biggest markets are being managed for margin, not expansion. Florida, still the largest, dropped 45 plans, the most of any state.
So what: in mature markets, winning share means taking it from someone.
| State | 2026 | 2027 | Change |
|---|---|---|---|
| Florida | 605 | 560 | −7.4% |
| Texas | 423 | 421 | −0.5% |
| California | 402 | 394 | −2.0% |
| Pennsylvania | 332 | 338 | +1.8% |
| New York | 218 | 224 | +2.8% |
Your next move
From what changed in 2027 to what you do about it
The 2028 bid, this AEP’s enrollment and next year’s network plan all start from these shifts. Here is where each team picks them up.
Want this read for your markets?
The county, payer and benefit view of AEP 2027 for the places you compete.
AEP 2027 questions, answered
Frequently asked questions
How many Medicare Advantage plans are available for 2027?
There are 5,558 Medicare Advantage plans for 2027, down 34 from 5,592 in 2026. It is the third straight annual decline, after drops of 123 in 2025 and 90 in 2026.
Which Medicare Advantage payers are expanding for 2027?
Devoted Health is expanding fastest, adding 313 plans (to 740) and entering 342 new counties with no exits. SCAN and Alignment also added plans. UnitedHealth, CVS and Humana held roughly flat, while Centene, HCSC and Molina each cut between 29% and 48% of their plans.
How many counties lost a Medicare Advantage payer for 2027?
1,150 counties lost at least one payer for 2027, and only 498 gained one. Across all payers there were 1,971 county exits and 1,088 county entries, a net loss of 883. Texas, Georgia and Minnesota saw the largest net losses.
Which benefits are Medicare Advantage plans cutting for 2027?
Meals (down 19.4%) and transportation (down 14.6%) are the largest supplemental benefit cuts, followed by chiropractic and over-the-counter allowances. Seven of eight in-home and caregiver benefits also lost plans. Core dental, vision and hearing benefits barely changed, and weight management grew 42.3%.
What is the maximum Part D deductible in 2027?
The maximum Part D deductible is $700 in 2027, up from $615 in 2026. 2,352 plans charge the full $700, and only 450 plans offer a $0 drug deductible, down from 2,940 in 2023.
Are D-SNPs and C-SNPs growing in 2027?
C-SNPs grew 35.6% to 754 plans. D-SNPs fell 3.0% to 1,052 after growing 15% in 2026, in the first year CMS’s new D-SNP alignment rules apply. Special needs plans now make up 35% of all Medicare Advantage plans, up from 26% in 2025.
What does the 2027 landscape file analysis show?
The CMS 2027 Medicare Advantage landscape file lists 5,558 plans, down 34 from 2026. 28 states and DC lost plans, PPOs fell by 89 while HMOs rose by 69, and 1,150 counties lost at least one payer. Special needs plans now make up 35% of all plans.
What are the key 2027 PBP file insights?
The 2027 plan benefit package (PBP) files show core dental, vision and hearing benefits holding steady, with 97.5% of plans covering eye exams. Meals fell 19.4%, transportation 14.6%, and seven of eight in-home and caregiver benefits lost plans, while weight management grew 42.3%. On Part D, only 450 plans keep a $0 drug deductible as the maximum rises to $700.
Where does this 2027 AEP Medicare Advantage analysis come from?
HealthWorksAI analyzed the CMS contract year 2027 Medicare Advantage landscape file, plan benefit package (PBP) files and plan crosswalk, compared with the same files for earlier years. Plan counts are unique plans in the landscape file. County moves count a payer as present if it offers any plan in a county, special needs plans included.
Source: HealthWorksAI’s 2027 AEP Medicare Advantage analysis of the CMS landscape, plan benefit package and plan crosswalk files, contract years 2023 to 2027 (2027 files released September and October 2026). Payer figures use parent organization, with documented alignment of renamed parents. Percentages are change in plan count, 2027 vs 2026, unless noted.