Be the first to read our insights
Get the latest Medicare Advantage, Medicaid, and Marketplace intelligence delivered straight to your inbox, and download this report as a PDF.
Thanks! Your download should start now. If it doesn't, open the PDF here.
Molina Healthcare Q3 2026 Earnings Insight: Critical Takeaways
This report is a HealthWorksAI breakdown of Molina Healthcare's Q3 2026 earnings call and its 2027 Medicare Advantage plan footprint, with a scorecard against our Q2 2026 flags, key leadership commentary, guidance, and what it means for competing health plans.
Section 1
Executive summary: Molina Healthcare Q3 2026 earnings takeaways
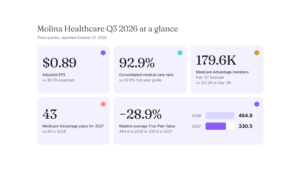
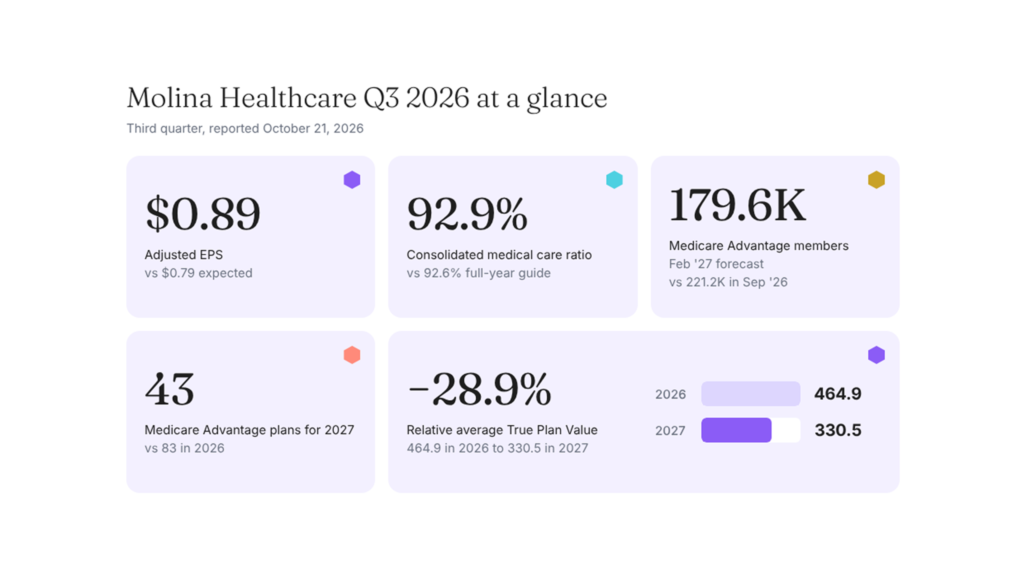
Molina Healthcare Q3 2026 earnings are a modest beat with a mixed outlook. Adjusted EPS was $0.89 against $0.79 expected, revenue was $11.08 billion against $10.86 billion expected, and full-year adjusted EPS guidance of at least $5.25 was reaffirmed. The consolidated medical care ratio was 92.9% and the adjusted pre-tax margin 0.6%. Shares were down 1.95% in pre-market trading as investors weighed a lower preliminary 2027 premium outlook, at least $45 billion against $46.5 billion before, and a $1 per share fourth-quarter drag from the new Florida CMS contract.
The 2027 Medicare Advantage data shows a sharp contraction: 43 plans against 83, a net loss of 39 counties (11 entered, 50 exited), and a forecast of 179,595 members by February 2027, down 18.8% from 221,159 in September 2026. Management is exiting its MAPD product for 2027 and concentrating Medicare on dual-eligible members. HealthWorksAI's relative True Plan Value for Molina fell by 28.9% for 2027, and none of the plans offered a $0 drug deductible.
1. Earnings
Adjusted EPS by quarter
Beat consensus of $0.79 by 12.7%. Full-year guidance of at least $5.25 reaffirmed, implying about $0.50 in Q4 after a $1 Florida drag.
2. Medical care ratio
Share of premiums paid out as medical costs, consolidated
70 basis points higher than Q2 and above the 92.6% full-year guide, which management called in line with expectations. Axis 92% to 94%, lower is better.
3. Medicare Advantage members
Thousands, HealthWorksAI enrollment data and forecast
−41,564 members, or −18.8%, as the MAPD product is discontinued.
4. The 2027 plan map
Molina Medicare Advantage plans, 2026 to 2027
−40 plans, or −48.2%. Counties go from 859 to 820, net −39 (11 entered, 50 exited).
5. True Plan Value
HealthWorksAI's proprietary measure of benefit value. Relative average across Molina plans
−28.9%
Molina's relative average True Plan Value falls 134.4 points across its 43 plans for 2027, and is down 54.4% from 2024.
Section 2
Key leadership commentary
The commentary below summarizes statements on Molina Healthcare's Q3 2026 earnings call, with one short verbatim sentence. The interpretations are ours.
On the quarter
The consolidated 92.9% medical care ratio reflects solid operating performance in a hard cost environment, and Medicaid, Medicare and Marketplace each landed where management expected, with the duals business giving the Medicare strategy a positive start.
Joe Zubretsky, President and Chief Executive Officer, Molina Healthcare
What this really means: in line is the headline. The $0.10 beat was planned, and fourth-quarter guidance of about $0.50 would be about $1.50 without the Florida CMS drag, as the CFO framed it.
On Medicaid
“The imbalance between rates and trend appears to have stabilized.”
Joe Zubretsky, President and Chief Executive Officer, Molina Healthcare
What this really means: both inputs moved up. The 2026 rate outlook rose to 4.5% from 4% and trend to 5.5% from 5%, so the full-year Medicaid MCR guide held at 92.9%. For 2027, early rates near 6% sit against trend of 5.5% to 6%.
On the Florida CMS contract
The launch went very smoothly: about 115,000 members and a $6 billion run rate, with Q4 running near a 99% medical care ratio and a 5% pre-tax loss. Getting to break-even in 2027 takes about 500 basis points, 200 from one-time reserves and 300 from better medical costs and G&A.
Joe Zubretsky, President and CEO, and Mark Keim, Chief Financial Officer, Molina Healthcare
What this really means: the reserve piece is accounting that rolls off. The 300 basis points of operating improvement is the part Molina still has to earn, and it is the line analysts kept returning to.
More from the call
On Medicare duals and MAPD
Duals are expected to earn a 1.4% pre-tax margin and $1.25 per share in 2026, while the MAPD product loses about $1 per share and is discontinued for 2027.
Joe Zubretsky, CEO, and Mark Keim, CFO
On Marketplace
The segment is still guided to a loss of about $0.75 per share, and the 2027 footprint shrinks to seven states, a loss management does not expect to recur.
Joe Zubretsky, CEO
On work requirements
Management still assumes about 6% Medicaid membership attrition in 2027, though 80% of its states lean toward policies that keep members enrolled, and Nebraska renewals have retained about 90%.
Joe Zubretsky, CEO, and Mark Keim, CFO
On 2027 rates
The January 1 renewal cohort is 55% of premium, draft rates are known for 80% of it at about 7% on average, and overall 2027 increases may approximate 6%.
Joe Zubretsky, CEO
On the 2027 outlook
Preliminary premium revenue is at least $45 billion, with $1.3 billion delayed by court proceedings on the Georgia and Texas awards, and EPS building blocks sum to more than $9.50.
Joe Zubretsky, CEO, and Mark Keim, CFO
On capital
Parent cash was about $600 million after $185 million of subsidiary dividends, operating cash flow was $629 million for nine months, and net debt to capital was 45%.
Mark Keim, CFO
Section 3
Did they deliver on what we flagged last quarter?
Measured against HealthWorksAI's own Molina Healthcare Q2 2026 Earnings Insight, covering the company's July 23, 2026 earnings call, which flagged five items worth tracking into Q3.
| What we flagged after Q2 2026 | What actually happened in Q3 2026 | Verdict |
|---|---|---|
| Marketplace guidance holding at a $0.75 full-year loss, or slipping further. | Held. Full-year Marketplace MCR guidance stays at 90% and the loss at about $0.75 per share, with a Q3 MCR of 92.5% in line with plan. The 2027 footprint falls to seven states. | Delivered |
| Q3 Medicaid MCR confirming the 5% trend and 4% rate assumptions. | Medicaid MCR was 93%, in line, and full-year guidance held at 92.9%. But both assumptions moved by 50 basis points, with rates now 4.5% and trend 5.5%. | Mixed |
| Early signs of how the Florida Medicaid contract ramps in Q4. | The contract was 22 days old at the call, with 115,000 members and a $6 billion run rate. Management called the launch very smooth, with Q4 near a 99% MCR and a 5% pre-tax loss, as planned. | On track |
| More 2027 state Medicaid rate updates being confirmed, with about 55% of premium on January 1 resets. | Draft rates are known for 80% of the January 1 cohort and average about 7%, pointing to overall 2027 rate increases near 6%. | Delivered |
| The $7.75 underlying earnings power and 2027 EPS building blocks of more than $10 holding as a guide-to-guide bridge. | The 2027 building blocks now sum to more than $9.50 and 2027 premium is at least $45 billion, down from $46.5 billion, on Georgia and Texas delays. The $7.75 figure was not restated in the call transcript. | Trimmed |
This scorecard shows two of five items delivered cleanly and one on track. The Medicaid assumptions and the 2027 outlook are the open cases: both moved the wrong way by small amounts, for reasons management framed as timing rather than a change in direction.
Section 4
What's actually changing
The beat was small, and the fourth quarter carries a Florida drag
Adjusted EPS of $0.89 beat consensus by $0.10, the adjusted G&A ratio was 6.3%, and the adjusted pre-tax margin was 0.6% for the quarter and 1.1% year to date. Full-year guidance of at least $5.25 implies about $0.50 in Q4, which includes a $1 drag from the Florida CMS contract. By business, Medicaid is expected to contribute about $5.75 per share for 2026, Medicare duals $1.25, MAPD a loss of $1 and Marketplace a loss of $0.75.
Medical care ratio
Share of premiums paid out as medical costs, consolidated
Axis runs 92% to 94%. Lower is better. The full-year guide is 92.6%.
Adjusted EPS by quarter
$ per share
Q4 implied is from full-year guidance. Ex-Florida adds back the $1 drag.
2026 EPS by business
$ per share, full-year expectation
The four lines sum to $5.25. Bar scale is $0 to $5.75.
Medicaid: rates and trend both moved up, and 2027 looks better
Management raised its 2026 rate outlook to 4.5% and its trend outlook to 5.5%, and believes current margins are the trough of a multi-year cycle. Legacy Medicaid is expected to earn a 1.6% pre-tax margin in 2026, against a 2029 target of 2.5% from Molina's investor day. Every 100 basis points of Medicaid MCR is worth about $5 per share.
Medicaid rates against trend
Annual increase, 2026 outlook and early 2027 view
Bar scale is 0% to 7%. The 2027 trend range includes about 50 basis points of conservatism, and about 1 point of 2026 trend is acuity shift.
Legacy Medicaid margin
2026 pre-tax margin against the 2029 target
The band is the path to the 2029 target. Scale 0% to 3%. Including Florida CMS, total Medicaid is expected to report about 1.2%, against 1.6% without it.
Medicaid membership
Same-store decline from work requirements and reverification
Bar scale is 0% to 8%. Cumulative losses of about 9% to 10% are expected over several years, with some pushed into 2028.
Early read from Nebraska
Work requirements, first months
Management said about 80% of its states lean toward policies that favor enrollment. Bar scale is 0 to 100%.
The 2027 map: 43 plans, down from 83
Molina goes from 83 Medicare Advantage plans to 43, a cut of 40 that is larger than the net decline of 34 plans across all payers, and from 859 counties to 820 (11 entered, 50 exited). The MAPD product is discontinued for 2027, which management said loses about $1 per share in 2026. On drug deductibles, plans in the top tier fall from 52 to 31 as the tier moves from $615 to $700, yet that is a higher share of a smaller book, and none of Molina's plans has a $0 drug deductible. Counts come from HealthWorksAI's analysis of the CMS 2027 plan benefit and crosswalk files.
Total plans
Molina Medicare Advantage plans, 2026 to 2027
−40 plans, or −48.2%.
Counties entered and exited
859 counties in 2026 to 820 in 2027, a net loss of 39
Molina exited 50 counties and entered 11. A county counts as exited only when Molina has no plan left in it.
Plans with a $0 drug deductible
Molina 0 of 43 plans in 2027, against 450 of 5,558 for all payers
Molina, 0%
All payers, 8.1%
Top drug deductible tier, Molina plans
The tier moved from $615 in 2026 to $700 in 2027
−40.4% in count, but from 62.7% of plans to 72.1%. A lower count in a higher tier says little about member costs on its own.
True Plan Value has fallen every year, and sharply for 2027
True Plan Value (TPV) is HealthWorksAI's proprietary measure of the value of plan benefits members realize above and beyond traditional Medicare, across Part C, Part D and Part B giveback. Molina's relative average falls from 725.2 in 2024 to 330.5 in 2027, a decline of 54.4%, with the steepest single-year drop of 28.9% for 2027.
Molina relative average True Plan Value
Relative average across Molina plans, 2024 to 2027
Year-over-year change in True Plan Value
Molina relative average
Averages blend plan and county mix, so read the direction more than the decimals.
Florida CMS: a smooth start, and a 500 basis point climb to break-even
The new Florida CMS contract serves about 115,000 children with complex medical and behavioral needs and carries a $6 billion annual run rate, with $1.5 billion of revenue in Q4. Management expects it to break even in 2027 and reach full target margins in year two.
From a 5% loss to break-even
Basis points of improvement needed in 2027
Q4 runs near a 99% MCR and a 5% pre-tax loss. The reserves are one-time, and most of the operating improvement is expected from MCR.
Florida CMS drag on 2026 EPS
$ per share
Expected to run at break-even or better in 2027. Bar scale is $0 to $1.50.
From the HealthWorksAI desk · The 2028 bid
Molina cut its Medicare Advantage book in half. Your 2028 bid decides who catches the members.
83 plans down to 43, an MAPD exit and 50 counties left behind: each was a trade-off between margin and membership, settled in June's bids. With about 41,600 members forecast to move and Molina's True Plan Value down 28.9% for 2027, the question for 2028 is which benefits would win them in your counties, and what keeping them would cost. That can be modeled, benefit by benefit, before anything is filed.
How plans test a benefit change before they bid →Section 5
Where the guidance goes from here
2027 EPS building blocks
$ per share, before any Medicaid margin recovery
Marketplace reaching at least break-even adds $0.75, and California's termination of the UIS program is a slight headwind, which brings the total to more than $9.50.
2027 premium revenue outlook
$ billion, at least
$1.3 billion of premium is delayed by the Georgia and Texas court proceedings. Known tailwinds of $6 billion compare with about $3 billion of headwinds from the MAPD exit, the Marketplace footprint and California's UIS termination.
Section 6
How the competitive picture is shifting
Molina is exiting MAPD rather than trimming benefits
It goes from 83 Medicare Advantage plans to 43 and concentrates on duals, a different path from peers that are keeping broad footprints.
The Medicaid cycle may be turning
Management sees current margins as the trough, with early 2027 rates near 6% and about 7% on the January 1 renewals it already knows.
Work requirements arrive in 2027
Molina expects about 6% membership attrition, with most states leaning toward policies that keep members enrolled.
The market weighed the outlook over the beat
Shares were down 1.95% in pre-market trading to $210.70 from $214.90, inside a 52-week range of $121.06 to $244.89.
Beyond Medicare Advantage: Molina signals from the call
RFP pipeline
Bids submitted or being finalized, against the investor day opportunity
Texas STAR Kids, Missouri, Arizona and Indiana make up the near-term bids. The Texas process is on hold in the state.
Embedded earnings
$ per share from known strategic initiatives
The 2027 harvest is $0.50 lower than before because the full benefit of operating leverage on the Georgia and Texas contracts is delayed.
Cash and balance sheet
$ million
Net debt to capital was 45% and days in claims payable were 44.
Section 7
What this means for your plan
If you bid against Molina in Medicaid
Molina has about $26 billion of RFPs in play, including Texas STAR Kids, Missouri, Arizona and Indiana, and its Georgia and Texas awards are still in court. Expect it to bid for growth where 2027 rates look favorable.
If you compete in Medicare duals or MAPD
Molina is building its Medicare strategy on duals and discontinuing MAPD for 2027, so its MAPD members are a displacement pool in overlapping counties during this annual enrollment period.
If you run an exchange book
Molina is cutting its Marketplace footprint to seven states for 2027 after a loss year, which may reprice or narrow options for members in the states it leaves.
If you look at benefit value
True Plan Value describes the value of benefits members realize. It does not measure enrollment, margin or Star Ratings, and averages blend plan and county mix.
Reading note: a county counts as exited only when Molina has no plan left in it, so plan-level changes can be larger than county-level ones.
How HealthWorksAI helps you act on this
HealthWorksAI brings payer moves by county, benefit value by plan and network fit into one platform, so a plan team can see where a competitor's 2027 map overlaps its own markets.
Your next move
From what changed in 2027 to what your team does about it
The 2028 bid, this AEP's enrollment and next year's network plan all start from these shifts. Here is where each team picks them up.
Common questions
Molina Healthcare Q3 2026 earnings: common questions
What were Molina Healthcare's Q3 2026 results?
Molina Healthcare reported adjusted earnings of $0.89 per share for Q3 2026, against $0.79 expected by analysts, on revenue of $11.08 billion against $10.86 billion expected. The consolidated medical care ratio was 92.9% and the adjusted pre-tax margin was 0.6%, or 1.1% year to date.
Did Molina Healthcare change its 2026 guidance?
No, it reaffirmed it. Adjusted EPS is still expected to be at least $5.25, with premium revenue of about $42 billion, a consolidated medical care ratio of 92.6% and an adjusted G&A ratio of 6.4%. Q4 adjusted EPS is expected to be about $0.50, after a $1 per share drag from the new Florida CMS contract.
Why did Molina's shares fall after the Q3 2026 report?
Shares were down 1.95% in pre-market trading to $210.70 from $214.90. Investors appeared to focus on a lower preliminary 2027 premium outlook of at least $45 billion, down from $46.5 billion because the Georgia and Texas contracts are delayed, and on the fourth-quarter drag from the Florida CMS contract.
What is Molina's True Plan Value for 2027?
HealthWorksAI's True Plan Value, a proprietary measure of benefit value, averages 330.5 on a relative basis across Molina's 43 Medicare Advantage plans for 2027, against 464.9 for 2026. That is a 28.9% decline, and the average is down 54.4% from 725.2 in 2024.
How many Medicare Advantage plans will Molina offer in 2027?
HealthWorksAI's analysis of CMS data shows 43 Molina Medicare Advantage plans for 2027 against 83 in 2026, in 820 counties against 859 (11 entered, 50 exited). Management is discontinuing its MAPD product for 2027 and focusing Medicare on dual-eligible members.
How many Medicare Advantage members does Molina have?
HealthWorksAI's enrollment data shows 221,159 Molina Medicare Advantage members in September 2026, and our forecast is 179,595 for February 2027, a decline of 41,564 or 18.8%. Actual annual enrollment results follow in early 2027.
What did Molina say about 2027?
Management expects premium revenue of at least $45 billion and preliminary EPS building blocks of more than $9.50 per share, without assuming any Medicaid margin improvement. It sees 2027 Medicaid rate increases near 6% against trend of 5.5% to 6%, and expects about 6% Medicaid membership attrition from work requirements.
What are Molina's drug deductibles for 2027?
HealthWorksAI's analysis of CMS data shows none of Molina's 43 Medicare Advantage plans has a $0 drug deductible for 2027. Plans in the top deductible tier fall from 52 at $615 in 2026 to 31 at $700 in 2027, a decline of 40.4% in count, though that is 72.1% of the smaller 2027 book against 62.7% in 2026.