Be the first to read our insights
Get the latest Medicare Advantage, Medicaid, and Marketplace intelligence delivered straight to your inbox, and download this report as a PDF.
Thanks! Your download should start now. If it doesn't, open the PDF here.
Centene Corporation Q3 2026 Earnings Insight: Critical Takeaways
This report is a HealthWorksAI breakdown of Centene Corporation's Q3 2026 earnings call, the stock reaction and its 2027 Medicare Advantage plan footprint, with a scorecard against what Centene promised at Q2 2026, key leadership commentary, guidance, and what it means for competing health plans.
Section 1
Executive summary: Centene Corporation Q3 2026 earnings takeaways
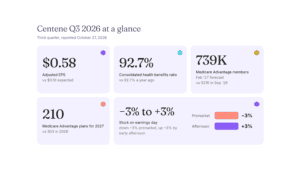
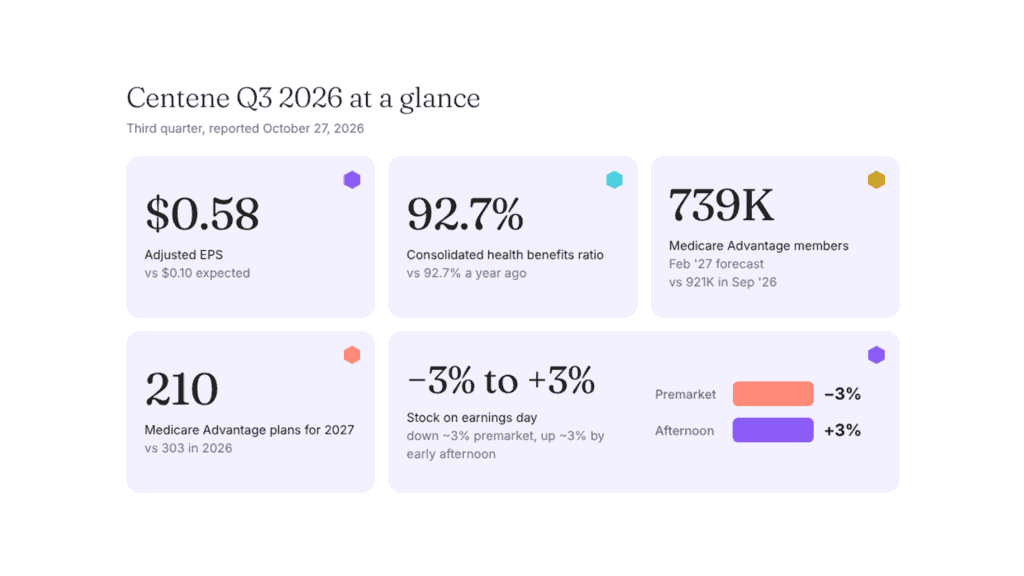
Centene Corporation Q3 2026 earnings are a large beat with a raised outlook. Adjusted EPS was $0.58 against $0.10 expected, revenue was $50.65 billion against $47.11 billion expected, and 2026 adjusted EPS guidance rose to more than $5.20 from more than $4.80. The consolidated health benefits ratio was 92.7%, Medicare Advantage is now on track to break even in 2026, a year early, and Marketplace is guided to the top of its 4.5% to 5% margin range. Two details temper the headline: Reuters reported LSEG's comparable adjusted profit at $0.16 against $0.10 expected, a smaller beat than the $0.58 headline, and about $0.50 of 2026 EPS will not recur, which sets a jump-off point of about $4.70 for 2027.
The stock opened weak and then reversed. Shares were down about 3% in premarket trading, then up about 3% by early afternoon as the call laid out 2027 growth off the $4.70 jump-off and the updated $5.20 guide. The 2027 Medicare Advantage data shows a deliberate pullback: 210 plans against 303, 1,692 counties against 1,853 (22 entered, 183 exited), and a forecast of 739,362 members by February 2027, down 19.7% from 920,535 in September 2026. HealthWorksAI's relative True Plan Value™ for Centene rises 7.7% for 2027, and 200 of its 210 plans sit in the top $700 drug deductible tier while none has a $0 deductible.
1. Earnings
Adjusted EPS, third quarter
Outlook raised to more than $5.20, from more than $4.80. Revenue $50.65B, ahead of the $47.11B expected.
2. Health benefits ratio
Share of premiums paid out as medical costs, consolidated
Unchanged from a year ago and better than the 92.84% analysts expected. The full-year ratio guide was lowered to 90.4% to 91.1%. Axis 92% to 94%, lower is better.
3. Medicare Advantage members
Thousands, HealthWorksAI enrollment data and forecast
−181,173 members, or −19.7%. Management expects Medicare Advantage membership to fall in 2027.
4. The 2027 plan map
Centene Medicare Advantage plans in its three largest states, 2026 to 2027
20262027
210 plans against 303, and net −161 counties. Scale 0 to 40 plans.
5. True Plan Value™
HealthWorksAI's proprietary measure of benefit value. Relative average across Centene plans
+7.7%
Centene's relative average True Plan Value™ rises 38.3 points across its 210 plans for 2027, after falling 9.0% for 2026, and is still 2.0% below 2025.
6. Stock reaction
CNC on earnings day, October 27, 2026
A weak open, then a reversal as the call framed 2027 growth.
52-week range $31.63 to $72.50. The stock was already near the top of its range.
Section 2
Key leadership commentary
The commentary below summarizes statements on Centene's Q3 2026 earnings call, with one short verbatim phrase. The interpretations are ours.
On the quarter
Third-quarter results were ahead of previous expectations, driven by outperformance in Medicare and in-line Medicaid and commercial results, which supports an improved full-year outlook and carries momentum into 2027.
Sarah London, Chief Executive Officer, Centene Corporation
What this really means: the beat was concentrated in Medicare, where standalone Part D drove most of the outperformance, and Reuters noted that LSEG's comparable adjusted profit was $0.16 against $0.10 expected, so the beat looks smaller on that basis.
On Medicare Advantage
“…break-even financial results in 2026, a year ahead of expectations.”
Sarah London, Chief Executive Officer, Centene Corporation
What this really means: break-even came a year early, but on a smaller book. Management expects Medicare Advantage membership to fall in 2027 as it narrows to markets where it can differentiate, and about 42% of members are in plans at or above 3.5 Stars for the 2028 plan year.
On 2027
Management expects to grow adjusted EPS in 2027 from both its updated $5.20 guidance and a normalized jump-off of about $4.70, which strips out roughly $0.50 of 2026 items that will not recur, with formal guidance due in early February.
Drew Asher, Executive Vice President and Chief Financial Officer, Centene Corporation
What this really means: Reuters put analyst 2027 EPS at $5.34 on LSEG data. That is above the $5.20 floor, so the market is already asking for growth beyond it, which is why 1/1 Medicaid rates and Marketplace pricing now matter more than the Q3 beat.
More from the call
On Medicaid
The Medicaid health benefits ratio was 93.6%, 30 basis points better than Q2 and in line with a 93.5% full-year forecast, with the composite rate holding near 5% and membership at 11.9 million.
Sarah London, CEO, and Drew Asher, CFO
On work requirements
States are taking a more methodical approach to eligibility checks, some January 1 draft rates already include explicit acuity provisions, and just over 40% of Medicaid revenue re-rates on January 1.
Sarah London, CEO
On Marketplace
Pre-tax margin is guided to about 5%, from about −1% in 2025, with year-end membership near 3.2 million and the Health Net commercial group business being exited over 18 to 24 months.
Drew Asher, CFO
On Part D
PDP margin is now in the mid to high 3s, membership is expected to tilt toward growth, and the opening 2027 margin is expected at 2% to 3% as the direct subsidy rises to $254.
Drew Asher, CFO
On costs and the balance sheet
Adjusted SG&A was 6.5% against 7.0% a year ago, most of the $480 million optimization charge was booked in Q3, and total debt is $15.0 billion, down from $18.5 billion at the end of 2024.
Drew Asher, CFO
On food as medicine
D-SNP members with richer healthy food benefits showed almost $200 per member per month in lower claims spend, with better blood pressure, HbA1c and BMI results.
Sarah London, CEO
Section 3
Did they deliver on what they promised last quarter?
Measured against the commitments in HealthWorksAI's Centene Q2 2026 Earnings Insight, covering the company's July 28, 2026 earnings call.
| What they promised in Q2 2026 | What actually happened in Q3 2026 | Verdict |
|---|---|---|
| Q3 slightly above breakeven, and Q4 a loss on normal seasonality. | Q3 adjusted EPS was $0.58, well above breakeven, and management called Q4 seasonality normal for its commission-driven businesses. | Delivered, improved |
| Medicaid membership down 8% to 9% for the full year. | Held. Members ended Q3 at 11.9 million, down 5% year to date, with a larger Q4 step-down as Florida CMS rolled off on October 1 and eligibility terminations began. | On track |
| Medicaid composite rate improving to roughly 5%. | Held at roughly 5%, with a Medicaid ratio of 93.6% that is 30 basis points better than Q2 and in line with the 93.5% full-year forecast. | On track |
| Marketplace margin of 4.5% to 5%, with about $180 million of one-time 2025 settlement in the quarter. | Moved to the top of the range, about 5%, while absorbing reserve strengthening for independent dispute resolution and other program integrity items. | Delivered, improved |
| Medicare Advantage breakeven within 2026, a year ahead of the original plan. | Confirmed. Break-even is on track for 2026, with better than break-even expected in 2027. | Delivered |
| PDP margin above 3%, up from an original 2%. | Raised again to the mid to high 3s, with PDP driving most of the Medicare outperformance. | Delivered, improved |
| A bridge for the roughly $0.50 of one-time items that will not repeat in 2027. | Delivered early. Management set about $4.70 as the 2027 jump-off point and expects to grow off both it and the raised $5.20 guide. | Delivered |
| Progress on the $480 million workforce and enterprise optimization program. | Most of the charge was booked in Q3, with the rest in Q4 and early 2027, outside adjusted results. Adjusted SG&A was 6.5% against 7.0% a year ago. | On track |
This scorecard shows five of eight items delivered, three of them improved on plan, and three on track, with none missed. The open items are Medicaid membership and the January 1 rate cycle, where rates and acuity have to stay aligned.
Section 4
What's actually changing
The beat was large, and the question is how much of it repeats
Adjusted EPS of $0.58 compares with $0.10 expected. Reuters reported that LSEG calculated comparable adjusted profit at $0.16 after excluding certain severance costs, a smaller beat than Centene's own adjusted figure, which sits outside the $480 million workforce charge. The 2026 outlook of more than $5.20 includes about $0.50 that management does not expect to recur, which sets a 2027 jump-off of about $4.70. The outlook rose on continued Medicare strength led by PDP, a Marketplace margin at the top of its range, and interest expense of about $610 million at the midpoint.
Health benefits ratio
Share of premiums paid out as medical costs, consolidated
Axis runs 92% to 94%. Lower is better. Analysts expected 92.84%.
How the beat reads
Q3 adjusted EPS, $ per share
Bar scale is $0 to $0.58. Adjustment definitions differ between Centene and LSEG.
2026 outlook and 2027 jump-off
Adjusted EPS, $ per share, more than
Bar scale is $0 to $5.20. About $0.50 of 2026 does not repeat.
The stock: a weak open, then a reversal
Shares were down about 3% in premarket trading after the release, according to Reuters, then reversed to trade up about 3% by early afternoon, as the call set out 2027 growth off the $4.70 jump-off and Medicare break-even a year early. Investing.com's transcript article cites $69.72, up 2.49% from a $68.03 prior close, against a 52-week range of $31.63 to $72.50, so the stock was already near the top of its range. After Q2 the shares fell despite a beat, which our Q2 report tied to about $0.50 of one-time items. Intraday readings are approximate and drawn from the sources cited.
Earnings-day path
Move versus the prior close, approximate
Premarket per Reuters at 6:20 a.m. ET. Early afternoon per Reuters at 1:14 p.m. ET.
52-week range
CNC share price, $
Range $31.63 to $72.50. $69.72 is about 93% of the way from the low to the high.
What the market is pricing
2027 EPS markers, $ per share
Consensus per LSEG via Reuters. Bar scale is $0 to $5.34.
Medicare: break-even a year early, on a smaller footprint
Medicare Advantage and standalone Part D both beat expectations, with PDP delivering most of the upside. Management expects Medicare Advantage to move from break-even in 2026 to better than break-even in 2027 while membership falls, and about 42% of members are at or above 3.5 Stars for the 2028 plan year, with 10% in four-star plans, in line with expectations.
PDP pre-tax margin
Management's view at each point
Bar scale is 0% to 4%. The 2027 view resets toward target as the Inflation Reduction Act effect fades.
Star Ratings, 2028 plan year
Share of Medicare Advantage members
Bar scale is 0 to 100%. Raw scores improved in preventive care and clinical outcomes, but cut points pressured results.
Medicaid: rates are holding, and membership keeps falling
Medicaid is right on its forecast, with a ratio of 93.6% against a 93.5% full-year view. Membership ended Q3 at 11.9 million, down 5% year to date, and Centene still expects year-end membership down 8% to 9%, with Florida CMS rolling off and eligibility terminations beginning on October 1. California's removal of the unsatisfactory immigration status population is a named 2027 headwind.
Medicaid membership decline
Against year-end 2025
Bar scale is 0% to 10%.
Composite rate
2026 Medicaid rate increase
Bar scale is 0% to 6%. Unchanged since the Q2 call.
January 1 re-rate
Share of Medicaid revenue
Some draft rates already include acuity provisions for work requirements.
Marketplace: from a loss to about a 5% margin
Marketplace is guided to a full-year pre-tax margin at the top of its 4.5% to 5% range, a swing of about 600 basis points from 2025, even after absorbing reserve strengthening for independent dispute resolution and program integrity items. Centene also decided to exit the Health Net commercial group business, about $4 billion, over 18 to 24 months.
Marketplace pre-tax margin
Full year
Bar scale is 0% to 5%, with 2025 shown at its absolute size.
Marketplace members
Millions
The market is still expected to contract slightly in 2027, with Centene's membership dependent on open enrollment.
The 2027 map: 210 plans, down from 303
Centene goes from 303 Medicare Advantage plans to 210, a cut of 93 that is more than twice the net decline of 34 plans across all payers, and from 1,853 counties to 1,692 (22 entered, 183 exited). Texas plans fall from 38 to 26 and Florida from 25 to 20, while Georgia holds at 15. Special needs plans are 100 of 210, or 47.6%. On drug deductibles, 200 plans sit in the top $700 tier against 210 at $615 in 2026, which is 95.2% of a smaller book, and none has a $0 deductible. Counts come from HealthWorksAI's analysis of the CMS 2027 plan benefit and crosswalk files.
Plans in the three largest states
Centene Medicare Advantage plans, 2026 to 2027
20262027
Texas 38 to 26, Florida 25 to 20, Georgia 15 to 15. Scale 0 to 40 plans.
Total plans
Centene Medicare Advantage plans, 2026 to 2027
−93 plans, or −30.7%.
Counties entered and exited
1,853 counties in 2026 to 1,692 in 2027, a net loss of 161
Centene exited 183 counties and entered 22. A county counts as exited only when Centene has no plan left in it.
Special needs plans, share of 2027 plans
Centene 100 of 210 plans, against 35% for all payers
Centene, 47.6%
All payers, 35%
Plans with a $0 drug deductible
Centene 0 of 210 plans in 2027, against 450 of 5,558 for all payers
Centene, 0%
All payers, 8.1%
Top drug deductible tier, Centene plans
The tier moved from $615 in 2026 to $700 in 2027
−4.8% in count, but from 69.3% of plans to 95.2%. A lower count in a higher tier says little about member costs on its own.
True Plan Value™ rebounds for 2027
HealthWorks AI TPV™ (True Plan Value) is a proprietary measure of the value of plan benefits members realize above and beyond traditional Medicare, across Part C, Part D and Part B giveback. Centene's relative average falls from $545.3 in 2025 to $496.3 in 2026, then rises to $534.6 in 2027, a gain of 7.7% that leaves it 2.0% below 2025.
Centene relative average True Plan Value™
Relative average across Centene plans, 2025 to 2027
Year-over-year change in True Plan Value™
Centene relative average
Averages blend plan and county mix, so read the direction more than the decimals.
From the HealthWorksAI desk · The 2028 bid
Centene shrank its map and raised its benefit value. Both were bid decisions.
93 fewer plans, 183 counties exited, 200 of 210 plans in the $700 deductible tier, and yet True Plan Value™ up 7.7% for 2027. Each was a trade-off between margin and membership, settled in June's bids. With about 181,000 members forecast to move, the question for 2028 is which of them your plans can win, and which benefits would do it. That can be modeled, benefit by benefit, before anything is filed.
How plans test a benefit change before they bid →Section 5
Where the guidance goes from here
2026 health benefits ratio guide
Full-year range, %
The midpoint improves 15 basis points. Scale 90% to 92%, lower is better.
The $0.50 that does not repeat
2026 adjusted EPS guide, $ per share
The $0.50 is about $180 million in Marketplace and $160 million in Medicare, largely PDP.
Debt reduction
Total debt, $ billion
$1.1 billion of senior notes repurchased since Q2, including the full 2027 notes. Debt to capital is 41.1%.
Section 6
How the competitive picture is shifting
Centene is shrinking Medicare Advantage on purpose
It goes from 303 plans to 210 and from 1,853 counties to 1,692, with management saying membership falls in 2027 while margin expands, a different path from payers keeping broad footprints.
Medicaid margin and membership still move in opposite directions
The composite rate is near 5% while membership is expected down 8% to 9%, and the Florida CMS contract rolled off on October 1.
Marketplace has turned
A margin swing of about 600 basis points from 2025 came with a decision to exit the Health Net commercial group business in California over 18 to 24 months.
The market looked past the beat
Shares were down about 3% premarket and up about 3% by early afternoon, near the top of a 52-week range of $31.63 to $72.50, as investors weighed 2027 growth off a $4.70 jump-off.
Beyond Medicare Advantage: Centene signals from the call
Part D membership
Millions
Growth is expected again in 2027 as the direct subsidy rises from $143 to $200 to $254.
Cash flow
Operating cash flow, $ billion
Q3 reflects over $3 billion of Medicaid pass-through payments held on the balance sheet at the end of Q2.
Medicaid acuity
Where acuity pressure shows up
Centene held more coverage for Q4 acuity, and expects the first state work requirements to begin in the fourth quarter.
Section 7
What this means for your plan
If you compete with Centene in Medicaid
Centene expects membership down 8% to 9% in 2026 and more attrition in 2027, so members leaving its plans may land with other managed care plans. The Florida CMS contract moved on October 1, and just over 40% of Centene's Medicaid revenue re-rates on January 1.
If you run Medicare Advantage in Centene's counties
Centene exits 183 counties and cuts 93 plans for 2027, with a forecast of about 181,000 fewer members by February. That is a displacement pool during this annual enrollment period, especially in Texas and Florida.
If you compete in Part D
Centene expects PDP membership growth in 2027 as the direct subsidy rises, with an opening margin view of 2% to 3%. Expect it to price for growth in the enhanced and auto-assign segments.
If you look at benefit value
True Plan Value™ describes the value of benefits members realize. Centene's rises 7.7% for 2027 while 200 of its 210 plans sit in the $700 drug deductible tier and none has a $0 deductible, so averages blend plan and county mix.
Reading note: a county counts as exited only when Centene has no plan left in it, so plan-level changes can be larger than county-level ones.
How HealthWorksAI helps you act on this
HealthWorksAI brings payer moves by county, benefit value by plan and network fit into one platform, so a plan team can see where a competitor's 2027 map overlaps its own markets.
Your next move
From what changed in 2027 to what your team does about it
The 2028 bid, this AEP's enrollment and next year's network plan all start from these shifts. Here is where each team picks them up.
Common questions
Centene Corporation Q3 2026 earnings: common questions
What were Centene Corporation's Q3 2026 results?
Centene reported adjusted EPS of $0.58 for Q3 2026, against $0.10 expected by analysts, on revenue of $50.65 billion against $47.11 billion expected. The consolidated health benefits ratio was 92.7%, unchanged from a year ago and better than the 92.84% analysts expected. Reuters noted that LSEG's comparable adjusted profit was $0.16.
Did Centene raise its 2026 guidance?
Yes. Adjusted EPS is now expected to be more than $5.20, up from more than $4.80. The full-year health benefits ratio guide improved to 90.4% to 91.1% from 90.5% to 91.3%, with SG&A at a 7.2% midpoint and interest expense near $610 million. Management said it expects to grow 2027 EPS from both the raised guide and a jump-off of about $4.70.
How did Centene's stock react to Q3 2026 earnings?
Shares were down about 3% in premarket trading on October 27, 2026, according to Reuters, then reversed to trade up about 3% by early afternoon. Investing.com's transcript article cites $69.72, up 2.49% from a $68.03 prior close, against a 52-week range of $31.63 to $72.50. These intraday readings are approximate.
What is Centene's True Plan Value™ for 2027?
HealthWorksAI's True Plan Value™, a proprietary measure of benefit value, averages $534.6 on a relative basis across Centene's 210 Medicare Advantage plans for 2027, against $496.3 for 2026. That is a 7.7% increase after a 9.0% decline for 2026, and it is still 2.0% below $545.3 in 2025.
How many Medicare Advantage plans will Centene offer in 2027?
HealthWorksAI's analysis of CMS data shows 210 Centene Medicare Advantage plans for 2027 against 303 in 2026, in 1,692 counties against 1,853 (22 entered, 183 exited). Texas falls from 38 to 26 plans and Florida from 25 to 20, while Georgia holds at 15. Management expects Medicare Advantage membership to decline in 2027.
How many Medicare Advantage members does Centene have?
HealthWorksAI's enrollment data shows 920,535 Centene Medicare Advantage members in September 2026, and our forecast is 739,362 for February 2027, a decline of 181,173 or 19.7%. Actual annual enrollment results follow in early 2027.
What did Centene say about 2027?
Management expects adjusted EPS growth in 2027 from both its raised 2026 guide and a jump-off of about $4.70, with Medicare Advantage moving above break-even, a higher Marketplace margin, PDP membership growth and a lower SG&A rate. Headwinds include Medicaid attrition from work requirements and a lower PDP margin. Formal guidance comes in early February.
What are Centene's drug deductibles for 2027?
HealthWorksAI's analysis of CMS data shows none of Centene's 210 Medicare Advantage plans has a $0 drug deductible for 2027. Plans in the top deductible tier go from 210 at $615 in 2026 to 200 at $700 in 2027, a decline of 4.8% in count, though that is 95.2% of the smaller 2027 book against 69.3% in 2026.