Be the first to read our insights
Get the latest Medicare Advantage, Medicaid, and Marketplace intelligence delivered straight to your inbox, and download this report as a PDF.
Thanks! Your download should start now. If it doesn't, open the PDF here.
Q3 2026 health plan earnings: beats and raises across seven payers, while the 2027 Medicare Advantage maps pull apart
This Q3 2026 health plan earnings report from HealthWorksAI compares UnitedHealth Group, CVS Health (Aetna), Elevance Health, Centene, Humana, Molina Healthcare and Alignment Healthcare, covering earnings calls held October 13 through November 6, 2026, and reads each against HealthWorksAI's 2027 plan, benefit and enrollment data, alongside public commentary on the health of the industry.
Section 1
Six of seven beat, five raised, and the market paid for quality, not for the beat
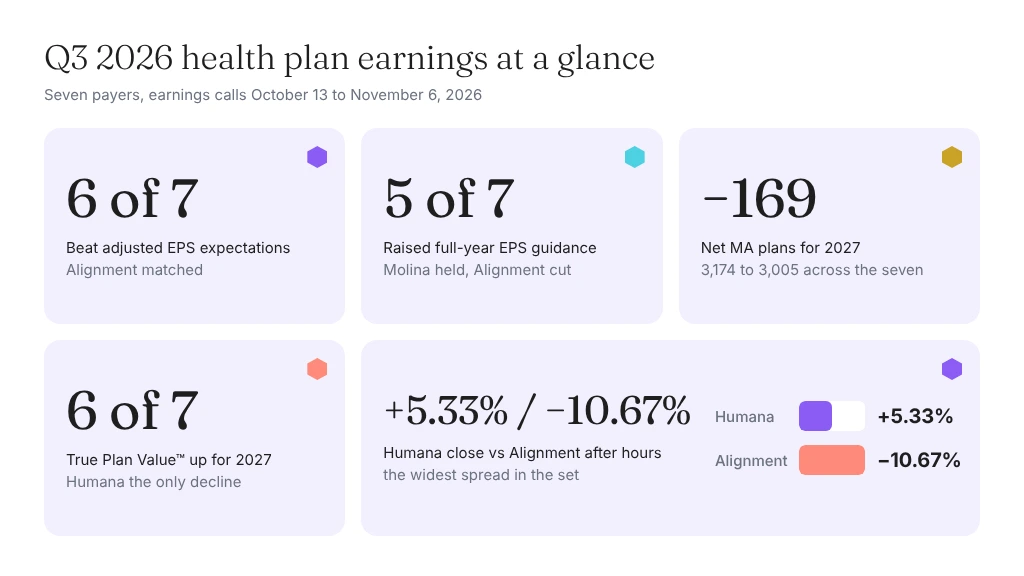
In Q3 2026 health plan earnings, six of seven payers beat adjusted EPS expectations and five raised full-year guidance, but stock reactions split. UnitedHealth rose 4.5% premarket after adjusted EPS of $4.69 against about $4.12 expected and its third raise of the year, and Humana closed up 5.33% after CMS's October 9 Star Ratings put 95% of its Medicare Advantage members in plans rated 4.0 Stars or higher. CVS and Elevance beat and still slipped, Molina fell 1.95% premarket on a lower 2027 premium outlook, Centene reversed from −3% to about +3%, and Alignment, whose EPS only matched, fell 10.67% after hours when it cut its profit outlook. These are premarket and intraday readings from each company report, and they are approximate.
Three things set Q3 apart from Q2. The quality of the beat matters more: Elevance's $6.99 included a net $1.85 per share of non-operating benefit against about $0.50 of operating outperformance, UnitedHealth leaned on $610 million of favorable reserve development, and about $0.50 of Centene's 2026 EPS will not recur. Star Ratings moved from risk to differentiator, with Humana at a member-weighted 4.17, UnitedHealth expecting to approach 75% of members in 4-plus-Star plans, and Alignment suing CMS after its largest California contract fell to 3.5 Stars. And 2027 is now visible in the plan filings, where the seven payers go in different directions.
HealthWorksAI's 2027 data shows the seven payers cutting a net 169 Medicare Advantage plans, from 3,174 to 3,005, while all payers fall by a net 34, so the rest of the market is adding plans. Centene (−93), Molina (−40) and Elevance (−37) cut hardest, Humana trims 26, and CVS (+12), Alignment (+9) and UnitedHealth (+6) add. Benefit value rises almost everywhere: our relative True Plan Value™ (TPV) is up for Centene (+7.7%), Molina (+7.4%), Alignment (+7.3%), CVS (+6.4%), Elevance (+3.2%) and UnitedHealth (+3.2%), with only Humana lower (−0.9%), and all seven sit above the $494 average of the 20 largest payers. Our enrollment forecasts agree: Alignment +14.8%, CVS flat, Humana −3.3%, Centene −19.7% and Molina −18.8%. Overall, our analysis suggests the set is dividing into payers that prune hard (Centene, Molina), payers that prune and hold (UnitedHealth, Elevance, CVS, Humana) and one that expands (Alignment), while benefit-value averages rise nearly everywhere, partly because lower-value plans exit, so annual enrollment results, which close December 7, will show which approach held.
Public commentary on the industry points the same way. Coverage from Healthcare Dive, Becker's Payer Issues, Fierce Healthcare, Axios and KFF describes 2026 margin rebuilt through exits, benefit cuts and repricing, with plans projecting Medicare Advantage enrollment near 34 million for 2027, about 6% lower, 11 insurers leaving the ACA Marketplace, and Medicaid rates catching up just as federal work requirements start on January 1. That fits our seven: UnitedHealth, Elevance, Centene and CVS raised with smaller books, Elevance and Centene both framed 2027 off a lower baseline than their raised 2026 guidance, and four of the seven lowered an operating or SG&A ratio year over year. The industry context section sets that commentary against our data.
Q3 2026 at a glance, seven payers
Alignment matched
Molina held, Alignment cut
3,174 to 3,005 across the seven
Humana the only decline
the widest spread in the set
Section 2
How the seven compare
Q3 2026 health plan earnings for all seven payers on one page: adjusted EPS against expectations, the reported ratio, guidance, membership and the stock reaction.
| Company | Adjusted EPS vs expected | Ratio, Q3 2026 | Full-year guidance | Core membership trend | Stock reaction |
|---|---|---|---|---|---|
| UnitedHealth Group | $4.69 vs about $4.12 | MCR 88.4% (89.9% a year ago), includes $610M favorable reserve development | Raised to at least $20.50, third raise this year | MA 7.61M, down 840K since Dec 31. Our forecast: about −215K by Feb '27 | Rose 4.5% premarket |
| CVS Health (Aetna) | $2.09 vs $1.65 | MBR 91.3% (92.8% a year ago) | Raised to at least $8.20, 2027 floor of at least $8.65 | Our MA forecast flat (+2,124 to 2.81M); 127 counties exited | Fell 4.9% premarket, about 11.8% on a later quote |
| Elevance Health | $6.99 vs about $4.70 | Benefit expense ratio 90.6% (70 bps better), net $1.85 non-operating benefit | Raised to at least $29 | Our MA forecast +0.7% (+10,302 to 1.52M) | Fell 1.2% premarket |
| Centene | $0.58 vs $0.10 (LSEG comparable $0.16) | HBR 92.7%, unchanged | Raised to more than $5.20 | Our MA forecast −19.7% (−181,173). Medicaid guided down 8% to 9% | −3% premarket, about +3% early afternoon |
| Humana | −$0.70 vs about −$1.00 | Insurance benefit ratio 93.7% vs guide above 94% | Adjusted raised to at least $9.50, GAAP to at least $15.09 | Individual MA 6.46M, up 23% YTD. Our forecast −3.3% (−211,492) | Early −0.8%, closed +5.33% |
| Molina Healthcare | $0.89 vs $0.79 | MCR 92.9% vs 92.6% full-year guide | Reaffirmed at least $5.25, 2027 premium trimmed to at least $45B | Our MA forecast −18.8% (−41,564) as MAPD is discontinued | Fell 1.95% premarket |
| Alignment Healthcare | −$0.04, in line (revenue $1.36B vs $1.31B) | Adjusted MBR 89.5% (87.2% a year ago) | Adjusted EBITDA cut to at least $100M, members and revenue raised | Members 301.2K, up 31.2%. Our forecast +14.8% (+43,977) | −1.47% in session, −10.67% after hours |
Ratios are as each company defines and discloses them (consolidated, segment or insurance-only), so they are not perfectly comparable across different business mixes. Expected EPS is the consensus cited in each company's HealthWorksAI report, and sources differ slightly. Stock readings are premarket or intraday and approximate. Forecasts are HealthWorksAI's September 2026 to February 2027 enrollment forecasts for individual Medicare Advantage.
Section 3
What's actually driving this quarter, industry-wide
Seven themes run across Q3 2026 health plan earnings, each with the payers it applies to.
Beat-and-raise is the baseline, so the market prices quality
Six of seven beat and five raised, yet the stock reactions ran from +5.33% (Humana close) to −10.67% (Alignment after hours). The winners paired a beat with a clear catalyst, Stars at Humana and a third straight raise at UnitedHealth. The decliners paired a beat with a question: the split at CVS, the quality of the beat at Elevance, the lower 2027 premium at Molina, and a profit cut at Alignment.
(UnitedHealth, Humana, CVS, Elevance, Molina, Alignment)
Quality of the beat: non-operating and one-time items are doing real work
Elevance's $6.99 included a net $1.85 per share of non-operating benefit against about $0.50 of operating outperformance. UnitedHealth's medical care ratio carried $610 million of favorable reserve development. About $0.50 of Centene's 2026 EPS will not recur, and Reuters put LSEG's comparable adjusted profit at $0.16 against Centene's $0.58. Humana's GAAP guidance jumped to at least $15.09 on non-cash valuation changes tied to its CenterWell joint ventures. Discount each before reading a trend into 2027.
(Elevance, UnitedHealth, Centene, Humana)
Star Ratings became a differentiator, and a lawsuit
After CMS's October 9 release, Humana put 95% of its Medicare Advantage members in 4-plus-Star plans against 20% a year earlier, with a member-weighted 4.17 that it expects to turn into a one-time 2028 tailwind. UnitedHealth said at least 69% of members are in 4-plus-Star plans and expects to approach 75%, while Healthcare Dive reports that its share fell from 81% in 2026 to 68% for 2027. About 42% of Centene's members are at or above 3.5 Stars. Alignment's largest California contract fell from 4.0 to 3.5 and the company sued CMS on October 9, with the effect on quality bonus payments coming in 2028.
(Humana, UnitedHealth, Centene, Alignment, CVS)
2027 footprints diverge: prune, hold or expand
Centene cuts 93 plans and exits 183 counties, Molina cuts 40 and discontinues MAPD, Elevance cuts 37 and nearly halves Florida, and Humana trims 26 plans and exits 61 counties. CVS adds 12 plans but exits 127 counties, UnitedHealth adds 6 selectively and Alignment adds 9 and enters 10 counties. Across the seven, 485 counties are exited against 171 entered, with county counts taken by payer.
(Centene, Molina, Elevance, Humana, CVS, UnitedHealth, Alignment)
Benefit value is rising almost everywhere, even as plans are cut
HealthWorksAI's relative True Plan Value™ rises for six of the seven: Centene (+7.7%), Molina (+7.4%), Alignment (+7.3%) and CVS (+6.4%) gain most, Elevance and UnitedHealth gain 3.2%, and only Humana slips (−0.9%). All seven sit above the $494 average of the 20 largest payers by total plan count for 2027, and Molina moves from below the $485 average in 2026 to above it. Averages blend plan and county mix, so exits of lower-value plans lift them even as press reports describe benefit cuts and higher cost sharing at the plan level, which makes the direction more reliable than the decimals.
(Centene, Molina, Alignment, CVS, Elevance, UnitedHealth, Humana)
Medicaid is stabilizing, not fixed
Elevance called 2026 the trough for its Medicaid margin, UnitedHealth called it the trough for core Medicaid margins, and Molina said the imbalance between rates and trend appears to have stabilized, with 2026 rates at 4.5% against trend of 5.5%. Centene's Medicaid ratio of 93.6% is on forecast but membership is still guided down 8% to 9% for the year. January 1 rate updates are now the swing factor for 2027.
(Elevance, UnitedHealth, Molina, Centene)
Part D and portfolio moves shape 2027 pricing
Humana prices 2027 Part D trend at 14% to 15%, up from 11% to 12%. Centene expects PDP membership growth with an opening 2027 margin of 2% to 3%, and Aetna reset its standalone Part D book while Caremark faces 2027 membership attrition. Portfolio moves add to the picture: CVS plans to split into two companies by the first half of 2028, and Humana replaced its Welsh Carson joint venture with one from BlackRock.
(Humana, Centene, CVS)
Section 4
Where 2027 margin has to come from, in public commentary
Beyond Q3 2026 health plan earnings, public reporting and analyst commentary on the Q3 calls and the 2027 filings describe an industry that rebuilt 2026 margin by pruning, and is now managing the trade-offs of 2027. We summarize five themes from Healthcare Dive, Becker's Payer Issues, Fierce Healthcare, Axios, KFF and others, and set each against the seven payers in this report.
Margin was rebuilt by pruning and benefit cuts, so 2027 leans on operations
Healthcare Dive reports that UnitedHealth raised guidance for the third time this year after cutting hundreds of Medicare Advantage plans, trimming benefits and shifting more cost to members for 2027, and expects its Medicare margin at the high end of 2% to 4%. Leerink analysts, cited by Fierce Healthcare, say Medicare Advantage insurers are prioritizing margin through benefit cuts, higher member cost sharing, PPO withdrawals and tighter broker commissions, and Stephens finds the average out-of-pocket maximum rising 9.1% for 2027, most at Centene. A HealthScape survey of 35 plan leaders, reported by Axios, found nearly 70% expecting less generous benefits.
What our seven show: UnitedHealth's Medicare Advantage membership is 840,000 below December, Centene cuts 93 plans, and relative True Plan Value™ still rises at six of the seven payers, partly because exits of lower-value plans lift the averages even as press reports describe plan-level benefit cuts. Elevance's 2027 baseline is at least $26.75 against a raised 2026 guide of at least $29, Centene's jump-off is about $4.70 against more than $5.20, and Molina's 2027 building blocks of more than $9.50 assume no Medicaid margin improvement. Operating-cost ratios improved at UnitedHealth (12.8% from 13.5%), Centene (adjusted SG&A 6.5% from 7.0%), Humana (11.3% from 12.6%) and Alignment (8.9% from 9.6%), while Elevance's rose 90 basis points to 11.3% on one-time investments.
Medicare Advantage enrollment is projected to fall, and members are being displaced
Becker's reports that plans expect about 34 million Medicare Advantage members in 2027, 47.4% of Medicare and roughly 6% lower according to Reuters, with plan options falling in 28 states. Bloomberg and Reuters report that UnitedHealth and Humana are discontinuing plans covering more than a million seniors, with a special enrollment period through February 28, 2027, and Humana has said its exits affect about 600,000 members. CMS has said plan projections have historically understated enrollment and expects a more robust 2027. Healthcare Dive adds that UnitedHealth's share of members in 4-plus-Star plans fell from 81% to 68%.
What our seven show: HealthWorksAI's forecasts show the displacement: Centene −19.7%, Molina −18.8% and UnitedHealth about −215K, while Humana's management expects growth and our forecast is down 3.3% (−211,492), so retention after December 7 is the test. County counts differ by source: Becker's counts service-area reductions, including partial ones (Centene 344, UnitedHealthcare 140, Aetna 123, Humana 57, Elevance 56), while HealthWorksAI counts only counties where a payer has no plan left.
Product mix is shifting toward HMOs, C-SNPs and duals
Fierce Healthcare reports that UnitedHealthcare is pulling back hardest from broker-sold PPOs and growing HMOs, and Becker's notes that Aetna adds 29 chronic condition plans and cuts 20 PPOs while most of Elevance's cuts come from dual-eligible plans. Healthcare Dive says Elevance will keep emphasizing HMOs and dual-eligible members in 2027. KFF adds that a new rule effective January 2027 generally limits insurers with an affiliated Medicaid plan to one D-SNP per county for full-benefit duals, which drove many D-SNP changes.
What our seven show: HealthWorksAI's national plan-type data shows the same shift: HMO plans rise by 69 for 2027 while PPO plans fall by 89, and chronic condition plans rise by 198 while non-SNP plans fall by 205. In our seven, CVS exits PPO in 117 counties, Humana's PPO exits cover 59 of its 61 exited counties, and Molina is leaving MAPD to concentrate on duals.
Medicaid rates are catching up to trend, and work requirements shift acuity
Healthcare Dive reports that states raised Medicaid rates in July, that Elevance now sees its 2026 Medicaid margin slightly better than the negative 1.75% it guided and still calls 2026 the trough, and that UnitedHealth describes a stubborn gap between state funding and utilization with a roughly negative 1% Medicaid margin this year. KFF-based coverage says federal work requirements start January 1, 2027 in most expansion states, asking adults aged 19 to 64 to report 80 hours a month of work or other approved activity, and that people who lose Medicaid because of the requirement cannot get Marketplace premium tax credits.
What our seven show: Molina's 2026 rates average 4.5% against trend of 5.5%, early 2027 rates sit near 6% against trend of 5.5% to 6%, and it plans for about 6% membership attrition with no margin improvement assumed. Centene's composite rate is near 5%, its Medicaid ratio of 93.6% is on forecast, membership is guided down 8% to 9% for 2026, and just over 40% of its Medicaid revenue re-rates on January 1. Elevance and UnitedHealth each called 2026 the trough.
The ACA Marketplace is shrinking, repricing and consolidating
KFF reports that insurers proposed a median premium increase of about 15% for 2027, that benchmark silver premiums are up 42% on average between 2025 and 2027, that 11 insurers are leaving some or all of their markets, and that the risk pool is shifting as healthier people drop coverage. Becker's reports that Cigna leaves the exchanges, affecting about 369,000 members, that Molina cuts more than half of its Marketplace states, and that Oscar and Kaiser expand. Healthcare Brew quotes Centene's CEO pricing for the expectation of additional acuity shifts as the market contracts.
What our seven show: Centene's Marketplace margin is guided to about 5% from about −1% in 2025, with year-end membership near 3.2 million and an exit from the Health Net commercial group business. Molina holds its Marketplace guidance at a $0.75 per share loss and cuts its 2027 footprint to seven states on its call, where Becker's counts six, and CVS has already left the individual exchange business.
Sources: Healthcare Dive, Becker's Payer Issues, Fierce Healthcare, Axios, KFF, Reuters and Bloomberg (as reported by Yahoo Finance), and Healthcare Brew, October to November 2026. Summaries are paraphrased. The lines marked "What our seven show" draw on the seven company reports and HealthWorksAI data in this page.
Section 5
Who's growing, who's holding, and who's shrinking on purpose
Q3 2026 health plan earnings and 2027 plan filings point to three membership postures.
| Posture | Companies | What it means |
|---|---|---|
| Growing, on purpose | Alignment (our forecast +14.8%) | 77 plans, up 9, and 10 counties entered with none exited, against a company target of at least 20% growth. It is the only payer in the set adding both plans and forecast members, at the cost of a profit reset. |
| Holding or selective | UnitedHealth, CVS, Elevance | UnitedHealth adds 6 plans and 4 counties on net while Medicare Advantage membership is 840,000 below December. CVS adds 12 plans but exits 127 counties, with flat forecast enrollment. Elevance cuts 37 plans and forecasts flat enrollment. |
| Shrinking on purpose | Centene (−19.7%), Molina (−18.8%), Humana (−3.3%) | Centene and Molina are cutting hardest, with Molina leaving MAPD. Humana trims 26 plans and 61 counties and forecasts membership up for 2027, while our forecast is down 211,492, so its retention data is the one to watch. |
Section 6
The 2027 Medicare Advantage map, seven payers side by side
HealthWorksAI's 2027 plan, benefit and enrollment data, set against Q3 2026 health plan earnings for the same seven payers.
Pruning, holding and expanding show up in plans, counties, benefit value and forecast enrollment
The seven payers go from 3,174 Medicare Advantage plans to 3,005 and enter 171 counties against 485 exited, with county counts taken by payer. Benefit value rises at six of the seven, led by Centene (+7.7%), Molina (+7.4%) and Alignment (+7.3%), with CVS up 6.4%, Elevance and UnitedHealth up 3.2% and Humana down 0.9%. All seven sit above the $494 average of the 20 largest payers by total plan count for 2027, and Molina moves from below the $485 average in 2026 to above it. Averages blend plan and county mix, so exits of lower-value plans can lift them. Plans in the top drug deductible tier fell at CVS (538 to 409), Elevance (95 to 33), UnitedHealth (224 to 182), Molina (52 to 31) and Centene (210 to 200), and rose at Humana (472 to 504) and Alignment (27 to 42), while plans with a $0 drug deductible range from none at Centene and Molina to 73 at Elevance.
Net change in Medicare Advantage plans
2026 to 2027, HealthWorksAI analysis of CMS data
The seven payers net −169 plans while all payers net −34. Bar scale is 0 to 93 plans.
Change in relative True Plan Value™
2026 to 2027, HealthWorksAI proprietary measure
All seven sit above the $494 top-20 average for 2027. Bar scale is 0% to 7.7%. Averages blend plan and county mix, so read direction more than decimals.
Forecast change in Medicare Advantage members
Thousands, September 2026 to February 2027, HealthWorksAI forecast
Bar scale is 0 to 215K members. The UnitedHealth figure is approximate.
| Company | Plans, 2026 to 2027 | Counties entered / exited | Members, Sep '26 to Feb '27 (forecast) | Relative True Plan Value™ | $0 drug deductible plans | Top-tier plans ($700, 2027) | Special needs share |
|---|---|---|---|---|---|---|---|
| UnitedHealth Group | 846 → 852 (+6) | 38 / 34 | ≈ −215K | $513.8 → $530.0 (+3.2%) | 10 | 182 (from 224) | 42.5% |
| CVS Health (Aetna) | 642 → 654 (+12) | 60 / 127 | 2.804M → 2.806M (+2,124) | $513.5 → $546.5 (+6.4%) | 9 | 409 (from 538) | 29.1% |
| Elevance Health | 345 → 308 (−37) | 26 / 30 | 1.51M → 1.52M (+10,302) | $544.1 → $561.3 (+3.2%) | 73 | 33 (from 95) | 46.8% |
| Centene | 303 → 210 (−93) | 22 / 183 | 920,535 → 739,362 (−181,173) | $496.3 → $534.6 (+7.7%) | 0 | 200 (from 210) | 47.6% |
| Humana | 887 → 861 (−26) | 4 / 61 | 6.448M → 6.237M (−211,492) | $501.5 → $496.9 (−0.9%) | 37 | 504 (from 472) | 27.9% |
| Molina Healthcare | 83 → 43 (−40) | 11 / 50 | 221,159 → 179,595 (−41,564) | $464.9 → $499.2 (+7.4%) | 0 | 31 (from 52) | 100% |
| Alignment Healthcare | 68 → 77 (+9) | 10 / 0 | 296,365 → 340,342 (+43,977) | $608.2 → $652.8 (+7.3%) | 32 | 42 (from 27) | 32.5% |
Source: HealthWorksAI analysis of CMS 2027 plan benefit and crosswalk files, and HealthWorksAI's enrollment forecast. A county counts as exited only when the payer has no plan left in it, and county counts overlap across payers. Top-tier plans are those in the highest drug deductible tier, $615 in 2026 and $700 in 2027, so a lower count can still be a higher share of a smaller book. True Plan Value™ is the relative average across each payer's plans and blends plan and county mix. The top 20 payers by total plan count average $494 for 2027, up from $485.
Section 7
The quarter, one card per company
One card per payer, summarizing its Q3 2026 health plan earnings, its 2027 map and what to watch.
UnitedHealth Group
Rose 4.5% premarketMCR 88.4%, includes $610M of favorable reserve development
A third raise of the year, adjusted EPS of $4.69 against $2.92 a year ago and about $4.12 expected, and a full-year outlook of at least $20.50. The margin story still leans partly on reserve development that has faded from $860 million in Q2, and Medicare Advantage membership is 840,000 below December by design. Its 2027 map is selective: 852 plans against 846, with Texas down 11.1% and Florida down 17.4%, and relative True Plan Value™ up 3.2% to $530.0.
“Our businesses are improving.”
Stephen Hemsley, Chairman and Chief Executive Officer, UnitedHealth Group
Watch: whether a full 2027 outlook backs management's view that consensus understates the opportunity, and how Medicare Advantage membership lands after annual enrollment.
CVS Health (Aetna)
Fell 4.9% premarket, about 11.8% on a later quoteMBR 91.3%, about 150 bps better than a year ago
A broad, Medicare-led beat: adjusted EPS $2.09 against $1.65, 2026 guidance raised to at least $8.20 and a 2027 floor of at least $8.65. The announced split into two companies by the first half of 2028 and a trough year for Health Services drew the attention. Aetna adds 12 plans but exits 127 counties, forecast enrollment is flat, and relative True Plan Value™ rises 6.4%, led by Part D and supplemental value.
“…2027 will reflect trough earnings for the segment.”
Brian Newman, Chief Financial Officer, CVS Health
Watch: AEP retention against the planned margin gains, and whether Health Services holds its floor of at least $7 billion in 2027.
Elevance Health
Fell 1.2% premarketBenefit expense ratio 90.6%, 70 bps better, net $1.85 non-operating benefit
A clear beat, adjusted EPS $6.99 against about $4.70 expected, with the outlook raised to at least $29, though a net $1.85 per share of non-operating benefit sat against about $0.50 of operating outperformance. The 2027 map is a deliberate pullback: 308 plans against 345, Florida cut from 103 to 52, 73 plans keeping a $0 drug deductible, and relative True Plan Value™ up 3.2% to $561.3 on the smaller book, while our forecast keeps enrollment roughly flat.
“…2026 as the trough for our Medicaid margin…”
Mark Kaye, Chief Financial Officer, Elevance Health
Watch: Medicaid rate adequacy through the January 1 cycle, and whether further state exits follow D.C.
Centene
−3% premarket, about +3% early afternoonHBR 92.7%, unchanged from a year ago
A large beat, adjusted EPS $0.58 against $0.10 expected, with the outlook raised to more than $5.20 and Medicare Advantage on track to break even a year early. About $0.50 of 2026 EPS will not recur, setting a 2027 jump-off near $4.70. The map shrinks hard: 210 plans against 303, 183 counties exited, a forecast of 739,362 members, down 19.7%, and 200 of 210 plans in the top deductible tier, yet relative True Plan Value™ rises 7.7%.
“…break-even financial results in 2026, a year ahead of expectations.”
Sarah London, Chief Executive Officer, Centene Corporation
Watch: Medicaid attrition against the 8% to 9% guide, and the 2027 bridge from the $4.70 jump-off in February.
Humana
Early −0.8%, closed +5.33%Insurance benefit ratio 93.7%, better than the guide of slightly above 94%
Adjusted EPS of −$0.70 against about −$1.00 expected, adjusted guidance raised to at least $9.50 and GAAP guidance to at least $15.09 on non-cash items. The Star Ratings result, 95% of members in 4-plus-Star plans and a member-weighted 4.17, set up a one-time 2028 tailwind. The map trims to 861 plans and 61 counties exited, relative True Plan Value™ is nearly flat (−0.9%) as Part D value rises and supplemental thins, and management expects 2027 membership up while our forecast is down 211,492.
“…the highest ratings Humana has ever achieved…”
Jim Rechtin, President and Chief Executive Officer, Humana
Watch: retention data once annual enrollment closes, and the December 10 investor event that updates its 2028 commitments.
Molina Healthcare
Fell 1.95% premarketConsolidated MCR 92.9% against a 92.6% full-year guide
A modest beat, adjusted EPS $0.89 against $0.79, with full-year guidance of at least $5.25 reaffirmed. Shares slipped on a lower preliminary 2027 premium outlook of at least $45 billion, from $46.5 billion, and a $1 per share fourth-quarter drag from the new Florida CMS contract. Molina is exiting MAPD and concentrating Medicare on duals: 43 plans against 83, 50 counties exited, a forecast of 179,595 members and relative True Plan Value™ up 7.4% to $499.2 on the smaller book.
“The imbalance between rates and trend appears to have stabilized.”
Joe Zubretsky, President and Chief Executive Officer, Molina Healthcare
Watch: January 1 Medicaid rates near 6% against trend of 5.5% to 6%, and the Florida CMS ramp toward break-even.
Alignment Healthcare
−1.47% in session, −10.67% after hoursAdjusted MBR 89.5%, up about 240 bps year over year
Revenue of $1.36 billion beat by about $50 million and membership grew 31.2%, but adjusted EBITDA guidance was cut to at least $100 million as appeals, skilled nursing and catastrophic claims ran high after a claims system migration. The 2027 map expands to 77 plans and 10 new counties, relative True Plan Value™ rises 7.3% to $652.8, and our forecast is 340,342 members. Its largest California contract fell to 3.5 Stars and the company sued CMS on October 9.
“…not to use the Q4 MLR as an annualized starting point…”
John Kao, Chairman and Chief Executive Officer, Alignment Healthcare
Watch: annual enrollment results in January against the target of at least 20% growth, fourth-quarter claims cost, and the Stars lawsuit.
Each card draws on the company's HealthWorksAI Q3 2026 report. Quotes are short phrases from each company's earnings call, and the interpretations are ours.
Section 8
Reading the peer set against your own book
How to read Q3 2026 health plan earnings against your own markets and members.
If you compete in Medicare Advantage
Displacement is real in the pruning payers' counties: Centene exits 183 counties, Humana 61 and CVS 127, and Molina is discontinuing MAPD, so their members must choose new plans this annual enrollment period. Alignment, CVS and UnitedHealth are adding plans, so expect fresh competition in selected markets.
If you compete on benefits
Relative plan value is rising at six of the seven payers, so a competitor's higher average is not proof of richer plans: exits of lower-value plans lift averages while press reports describe higher cost sharing and PPO withdrawals. Benchmark your 2028 bid plan by plan and county, not on payer averages.
If you are Medicaid-exposed
Three payers called 2026 a margin trough and January 1 rate updates are the swing factor. Centene expects membership down 8% to 9% this year and Molina expects about 6% attrition from work requirements in 2027.
If you benchmark Stars and quality
Humana's 95% of members in 4-plus-Star plans and UnitedHealth's path toward 75% raise the bar, while Alignment's 3.5-Star California contract shows how one contract can move bonus funding. Star performance is now a visible earnings lever.
Reading note: HealthWorksAI's enrollment counts and forecasts cover individual Medicare Advantage and use a different basis from company-reported membership, so figures differ. Premarket and intraday stock readings are approximate. Top-20 payer averages use total plan counts. The industry context section summarizes public reporting from the outlets named there, and press counts of county exits use different definitions from HealthWorksAI's.
How HealthWorksAI helps you act on this
HealthWorksAI brings payer moves by county, benefit value by plan and network fit into one platform, so a plan team can see where a competitor's 2027 map overlaps its own markets.
From the HealthWorksAI desk · The 2028 bid
Seven payers made seven different bets. The next bid season has started.
Centene, Molina and CVS pruned their maps and the plans that remain score higher on benefit value, Elevance and UnitedHealth added modest value on smaller or selective books, Humana slipped, and Alignment expanded. Each was a trade-off between margin and membership, settled in the bids filed this June, and with the 2027 benefit files public, plan design teams are already shaping 2028.
The useful question has changed from what competitors cut to what members would do if a plan cut the same thing, or kept it when others did. That can be modeled, benefit by benefit, before anything is filed.
How plans test a benefit change before they bid →Section 9
What to watch next quarter, across the full peer set
The dates and decisions that will test what Q3 2026 health plan earnings signaled.
| Annual enrollment | October 15 to December 7, 2026, with results in January: whether Alignment's forecast of +14.8% and Centene's −19.7% hold, and what happens to Humana's expected membership growth against our forecast of −3.3%. |
| Q4 results and 2027 guidance | Late January to February 2027: UnitedHealth's full 2027 outlook, Elevance's growth of at least 12% off a $26.75 baseline, CVS's formal guidance off its $8.65 floor, Centene's bridge from about $4.70, and Molina's initial 2027 guidance. |
| Humana investor event | December 10, 2026: how Humana sizes its one-time 2028 Star Ratings tailwind and updates its 2028 commitments. |
| Medicaid rates and work requirements | January 1, 2027 rate updates and the start of federal work requirements in most expansion states: whether rates near 6% keep pace with trend of 5.5% to 6% and with the change in acuity. |
| CMS Advance Notice | Typically late January to early February: the payment direction for 2028, after CMS dropped its proposal to hold 2027 rates flat, in the same weeks several payers give formal 2027 guidance. |
| ACA open enrollment | Open enrollment, with a December 15 deadline for January 1 coverage, and early-2027 effectuation data: where departing Cigna members land and how a smaller, sicker pool prices for 2028. |
| D-SNP alignment | The January 2027 rule limiting insurers with an affiliated Medicaid plan to one D-SNP per county for full-benefit duals, and how it reshapes dual-eligible enrollment at Humana, Elevance, Molina and others. |
| Stars and litigation | Alignment's lawsuit against CMS over its 2027 Star Ratings, and the first read-through of bonus year 2028 funding across the set. |
| Portfolio moves | CVS's separation process through 2028, the Florida CMS ramp at Molina, and Humana's Illinois Medicaid go-live in January 2027. |
Common questions
Q3 2026 health plan earnings: common questions
How did the seven major payers do in Q3 2026?
Across Q3 2026 health plan earnings, six of seven beat adjusted EPS expectations and five raised full-year guidance. UnitedHealth, CVS, Elevance, Centene and Humana raised, Molina reaffirmed, and Alignment cut its adjusted EBITDA outlook. Stock reactions were mixed, from Humana's 5.33% close gain to Alignment's 10.67% after-hours drop.
Which payers raised guidance in Q3 2026?
UnitedHealth raised adjusted EPS to at least $20.50, CVS to at least $8.20, Elevance to at least $29, Centene to more than $5.20 and Humana to at least $9.50 on an adjusted basis. Molina reaffirmed at least $5.25. Alignment raised membership and revenue guidance but lowered adjusted EBITDA to at least $100 million.
How did the stocks react to Q3 2026 earnings?
UnitedHealth rose about 4.5% premarket, Humana closed up 5.33%, and Centene moved from about −3% premarket to about +3% in early afternoon. Elevance fell about 1.2% premarket, Molina about 1.95% premarket, CVS 4.9% premarket and about 11.8% on a later quote, and Alignment fell 10.67% after hours. These readings are approximate and come from each company's report.
How many Medicare Advantage plans do the seven payers file for 2027?
HealthWorksAI's analysis of CMS data shows 3,005 plans for 2027 against 3,174 in 2026, a net decline of 169, while all payers together fall by a net 34. Centene falls by 93, Molina by 40, Elevance by 37 and Humana by 26, while CVS adds 12, Alignment 9 and UnitedHealth 6.
How does True Plan Value™ compare across the seven payers for 2027?
HealthWorksAI's relative True Plan Value™ rises for Centene (+7.7%), Molina (+7.4%), Alignment (+7.3%), CVS (+6.4%), Elevance (+3.2%) and UnitedHealth (+3.2%) and slips for Humana (−0.9%). All seven sit above the $494 average of the top 20 payers by total plan count for 2027, up from $485 in 2026. Averages blend plan and county mix, so exits of lower-value plans can lift them.
What does HealthWorksAI forecast for Medicare Advantage enrollment?
For individual Medicare Advantage between September 2026 and February 2027, the forecast is Alignment +43,977 (+14.8%), Elevance +10,302 (+0.7%), CVS +2,124, Humana −211,492 (−3.3%), Centene −181,173 (−19.7%) and Molina −41,564 (−18.8%), with UnitedHealth about 215,000 lower.
What does public commentary say about the health of the industry heading into 2027?
Coverage from Healthcare Dive, Becker's Payer Issues, Fierce Healthcare, Axios and KFF describes margin rebuilt in 2026 through exits, benefit cuts and repricing. Plans project Medicare Advantage enrollment near 34 million for 2027, about 6% lower, with options falling in 28 states and a shift toward HMOs and chronic condition plans. Medicaid rates are catching up to trend as federal work requirements start January 1, 2027, and 11 insurers are leaving the ACA Marketplace as premiums rise again. Our seven payers' data is consistent with most of that.
What happened with Star Ratings in the October 2026 release?
Humana put 95% of its Medicare Advantage members in plans rated 4.0 Stars or higher, with a member-weighted 4.17 for bonus year 2028. UnitedHealth said at least 69% of members are in 4-plus-Star plans and expects to approach 75%, while Healthcare Dive reports that its share fell from 81% in 2026 to 68% for 2027. Alignment's largest California contract fell to 3.5 Stars and the company sued CMS on October 9.