Be the first to read our insights
Get the latest Medicare Advantage, Medicaid, and Marketplace intelligence delivered straight to your inbox, and download this report as a PDF.
Thanks! Your download should start now. If it doesn't, open the PDF here.
Humana Q3 2026 earnings: a beat, a raised outlook and near-record Star Ratings, as the 2027 map shrinks
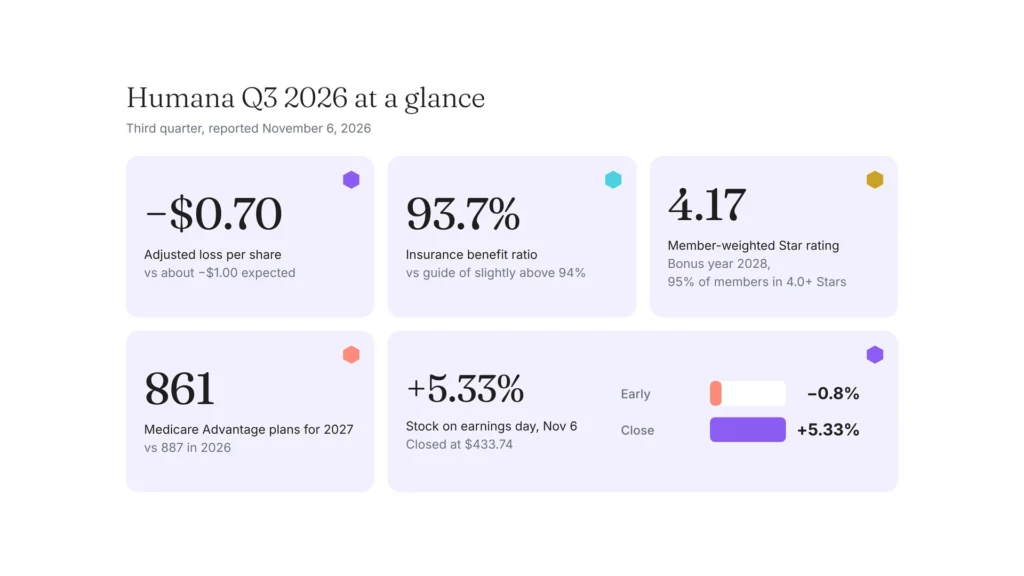
Humana reported an adjusted loss of $0.70 per share against about a $1.00 loss expected, raised its 2026 adjusted EPS outlook to at least $9.50 and reported a member-weighted Star rating of 4.17 for bonus year 2028. It filed 861 Medicare Advantage plans for 2027, down from 887, while exiting 61 counties. This page reads the earnings call, the stock reaction and HealthWorksAI's 2027 plan and benefit data together.
Section 1
Executive summary: Humana Q3 2026 earnings takeaways
Humana's Q3 2026 results beat expectations. The adjusted loss was $0.70 per share against about a $1.00 loss expected (Yahoo Finance; Zacks shows $1.03), GAAP EPS was $1.33, and revenue rose 26% to $41.2 billion against $40.87 billion expected, driven by Medicare membership growth and higher per member premiums. The Insurance segment benefit ratio was 93.7%, better than management's guide of slightly above 94%, though up from 91.1% a year ago on the bonus year 2026 Star Ratings headwind, new members and thinner prior period reserve development. Management raised 2026 adjusted EPS guidance to at least $9.50 from at least $9.00, against a $9.16 consensus, and GAAP EPS guidance to at least $15.09 from at least $6.52, mostly on non-cash valuation changes tied to its CenterWell joint ventures. Shares slipped about 0.8% early, then closed up 5.33% at $433.74.
The bigger story is Star Ratings and 2027. Humana's CMS Star Ratings for 2027, announced Oct 9, 2026, put 95% of its Medicare Advantage members in plans rated 4.0 Stars or higher, against 20% for 2026. On the Q3 call management tied this to what it called bonus year 2028 (BY 28), reporting a member-weighted Star rating of 4.17, close to the highest it has achieved. Management will keep running the business to a top quartile level, so it expects a one-time tailwind in 2028, part reinvested and part returned to shareholders. For 2027 it priced for margin first, retention second and growth a distant third, and says AEP is running ahead of its initial expectations, with strong recapture of members from exited plans and membership now expected to be up. Individual Medicare Advantage membership reached 6.46 million at Sep 30, up 23% from year end, and D-SNP membership rose 25% to 958,300 from 765,800 a year earlier.
HealthWorksAI's analysis of CMS data shows Humana going from 887 Medicare Advantage plans to 861 for 2027, entering 4 counties and exiting 61, against an all-payer net decline of 34 plans (5,592 to 5,558). Florida (122 plans), Texas (72) and Virginia (49) stay its largest states, with Virginia adding four plans. HealthWorksAI's relative True Plan Value™ (TPV) slips 0.9% to $496.9, close to the $494 average across the 20 largest payers by total plan count. Part D value rises $273.2 to $284.2 while supplemental benefits fall $69.8 to $62.8, and plans in the top $700 drug deductible tier rise to 504, or 58.5% of plans, from 472 at $615 in 2026. Management said its portfolio protects the benefits seniors rank as most important. Our data points to value shifting toward Part D, where Humana expects 2027 cost trend of 14% to 15%, while supplemental benefits thin. Overall, our analysis suggests Humana is narrowing its footprint and pricing for margin while near-record Stars support the product, so the key test is retention once AEP closes.
1. Earnings
Adjusted loss per share, third quarter
About $0.30 smaller loss than expected. Revenue was $41.2B, ahead of the $40.87B expected. Outlook raised to at least $9.50.
2. Insurance benefit ratio
Share of premiums paid out as benefits, Insurance segment
Better than the guide of slightly above 94%, but up 260 bps from a year ago on the Star Ratings headwind. Axis 91% to 95%, lower is better.
3. Membership growth, year to date
Change from Dec 31, 2025 to Sep 30, 2026, thousands
Individual MA reached 6.46M, up 23.0% against a guide of about 25%. PDP and group MA both count about 350K decoupled group members. Bar scale is 0 to 1,600K.
4. The 2027 plan map
Humana Medicare Advantage plans in its three largest states, 2026 to 2027
20262027
861 plans against 887, with 4 counties entered and 61 exited. Scale 0 to 130 plans.
5. Star Ratings
Bonus year 2028, as reported by Humana
For 2027 Star Ratings, announced Oct 9, 2026, against 20% for 2026. Bar scale is 0% to 100% of members.
4.17
Member-weighted Star rating for bonus year 2028, which management said approaches the highest Humana has achieved and significantly exceeds its top quartile goal.
6. True Plan Value™
HealthWorksAI's proprietary measure of benefit value. Relative average across Humana plans
−0.9%
Humana's relative average True Plan Value™ slips 4.6 points across its 861 plans for 2027, to $496.9, after rising in 2026. It sits about 0.6% above the $494 top 20 payer average.
7. Stock reaction
Humana on earnings day, Nov 6, 2026
Closed at $433.74 against a $411.79 prior close, after an intraday high of $444.00. The early reading is from Yahoo Finance before the open.
52-week range $163.11 to $456.50. The close sat about 92% of the way up from the low, against about 85% at the prior close.
Section 2
Key leadership commentary
The commentary below summarizes statements on Humana's Q3 2026 earnings call, with one short verbatim phrase. The interpretations are ours.
On the quarter
Execution is strong and improving, and results are moving from on plan toward ahead of plan. Cost trends are in line to better than expected for both new and existing members, which supports the higher full-year outlook, and individual Medicare Advantage pre-tax margin remains on track to double this year, excluding the Star Ratings headwind.
Jim Rechtin, President and Chief Executive Officer, and Celeste Mellet, Chief Financial Officer, Humana
What this really means: the beat came from cost trend running at the lower end of the 7% to 8% range, with inpatient and Part D both better than expected, rather than from a change in strategy. The quarter still shows the Star Ratings headwind and thinner reserve releases, so the raise is a modest step on a year guided to fall from 2025.
On Star Ratings
“Our Star Ratings approach the highest ratings Humana has ever achieved, with a member-weighted Star rating of 4.17.”
Jim Rechtin, President and Chief Executive Officer, Humana
What this really means: the bonus year 2028 result is well above the top quartile level Humana says it needs for a sustainable 3% margin. Because the business will be run to top quartile, not top decile, the surplus becomes a one-time 2028 tailwind, part reinvested and part returned to shareholders, with the size to come later and a 30% offset already shared with value-based care providers.
On 2027
Margin was the number one priority in bids, retention second and growth a distant third. There are no known headwinds for 2027 beyond carrying this year's Stars headwind, and individual Medicare Advantage margin should improve materially on both a Stars-adjusted and an unadjusted basis.
Celeste Mellet, Chief Financial Officer, and Jim Rechtin, President and Chief Executive Officer, Humana
What this really means: Humana is pricing 2027 for a higher 8% to 9% cost trend, with Part D at 14% to 15%, and expects most of the margin gain to come from pricing. Fewer new members should also lower first-year costs, so the open question is retention, which management says it cannot see yet.
More from the call
On AEP 2027
AEP performance is ahead of initial expectations. Recapture of members affected by planned exits has been particularly strong and new sales are ahead of plan, helped by distribution partners, and membership is now expected to be up for 2027. Retention data is not available yet.
Jim Rechtin, President and CEO
On cost trend
2026 trend is at the lower end of the expected 7% to 8%, with favorable inpatient admissions and cost per admission and favorable Part D. For 2027, trend is expected at 8% to 9%, with Part D at 14% to 15% from 11% to 12% this year, driven by the health technology pipeline and priced into both MAPD and PDP bids.
Celeste Mellet, CFO
On the larger players
The larger players all appear better positioned than expected for AEP, given the number of plan exits across most of them, with some consolidation of smaller plans helping the larger ones.
Celeste Mellet, CFO
On CenterWell
Primary care costs rose for a particular set of patients in one geography, linked to some outlying facilities in Florida. CenterWell and payer partners, including Humana, have changed contract terms, benefit design and network management, and the enterprise impact is not meaningful.
Celeste Mellet, CFO
On capital and the balance sheet
A new joint venture with BlackRock replaces the Welsh Carson joint venture, cutting the cost of capital and removing a 2027 put option. It should lower the debt-to-capitalization ratio by about 130 basis points in Q4, and the Gentiva stake sale should bring about $900 million before tax.
Celeste Mellet, CFO
On group Medicare Advantage
Recontracting has improved group Medicare Advantage margin by 500 basis points, excluding the Stars headwind, with the full benefit visible once Stars return in 2028.
Celeste Mellet, CFO
On Medicaid
Humana's Medicaid footprint now spans 13 states, 11 active, with Georgia and Texas awarded and pending. Membership grew by about 104,000 in 2026, largely from the Michigan HIDE SNP, the statewide Illinois FIDE SNP and the South Carolina duals carve-in.
Jim Rechtin, President and CEO
Section 3
Did they deliver on what we flagged last quarter?
Measured against the items in HealthWorksAI's Humana Q2 2026 Earnings Insight, covering the company's Jul 29, 2026 earnings call, which flagged five items to watch and the guidance that had to hold.
| What we flagged in Q2 2026 | What actually happened in Q3 2026 | Verdict |
|---|---|---|
| Whether Humana's claimed improvement across 11 of 12 Star measures would show up in the actual bonus year ratings. | It did. Humana's 2027 Star Ratings, announced Oct 9, 2026, put 95% of members in plans rated 4.0 Stars or higher, against 20% for 2026. On the Q3 call management tied this to bonus year 2028 and a member-weighted 4.17 Stars, significantly above the top quartile goal behind the 2028 commitment. | Delivered, improved |
| Whether full-year GAAP EPS guidance would be cut a third time or hold at at least $6.52. | It rose to at least $15.09. The increase comes mostly from non-cash valuation changes on minority interest investments tied to the CenterWell joint ventures, as the new BlackRock joint venture replaced the Welsh Carson one, not from operations. | Mixed |
| How many of the roughly 600,000 members affected by Humana's 2027 plan exits it recaptures during AEP. | Management called recapture particularly strong and expects membership to be up for 2027, but retention data is not in yet. HealthWorksAI data shows 861 plans against 887, with 61 counties exited. | On track |
| Illinois Medicaid managed care going live in Jan 2027, with Humana as the only new statewide entrant. | The go-live is still ahead and was not addressed on the call. Medicaid membership grew by about 104,000 in 2026, including the statewide Illinois FIDE SNP, a separate dual-eligible plan, not the Medicaid managed-care contract itself, and the footprint now spans 13 states. | Pending |
| The appeal of Humana's challenge to its 2025 Star Ratings. | It was not discussed on the call. The release still lists the appeal as ongoing, with no assurance it succeeds. | Pending |
| Full-year 2026 adjusted EPS guidance of at least $9.00, held all year. | Raised to at least $9.50, above the $9.16 consensus, on cost trend at the lower end of the expected range. | Delivered, improved |
| The Insurance segment benefit ratio holding to guidance, with the full-year guide at 92.75% plus or minus 25 basis points. | The Q3 ratio was 93.7%, better than the guide of slightly above 94%, and the full-year guide was left unchanged. | Delivered, improved |
| Individual Medicare Advantage membership growth of about 25% for 2026. | Membership reached 6.46 million at Sep 30, up 23.0% from year end, with the guide unchanged and D-SNP membership up 25% to 958,300 from 765,800 at Sep 30, 2025. | On track |
This scorecard shows three of eight items delivered, all of them improved on plan, two on track, one mixed and two pending, with none missed. The open items are AEP retention, the Illinois go-live and the Star Ratings appeal. The BlackRock joint venture was not on the Q2 list.
Section 4
What's actually changing
A smaller loss than expected, on better cost trend
The adjusted loss of $0.70 per share was about $0.30 better than the roughly $1.00 consensus, and revenue of $41.2 billion was up 26% and above the $40.87 billion forecast. The Insurance segment benefit ratio of 93.7% beat the guide of slightly above 94% but rose from 91.1% a year ago, reflecting the bonus year 2026 Star Ratings headwind, new members who run at a higher ratio, and prior period development of $67 million against $275 million a year earlier. The consolidated operating cost ratio improved to 11.3% from 12.6% on operating leverage and cost cutting. CenterWell revenue rose to $7.2 billion, but its adjusted income from operations fell to $291 million from $358 million, partly on higher primary care costs in one geography.
Insurance benefit ratio against the guide
Q3, %
The full-year guide of 92.75% plus or minus 25 bps was left unchanged. Scale 90% to 95%, lower is better.
Prior period reserve development
Favorable, $ million
Lower favorable development was anticipated in 2026. Part of it belongs to provider risk-sharing arrangements. Bar scale is $0 to $913M.
The stock: a soft start, then a 5% gain
Yahoo Finance reported shares down about 0.8% after the release, ahead of the 8:00 a.m. ET question and answer session. By the close on Nov 6, 2026, Humana was up 5.33% at $433.74 from a $411.79 prior close, after trading between $411.56 and $444.00, within a 52-week range of $163.11 to $456.50. The raised outlook beat the $9.16 consensus, and management said AEP is running ahead of its initial expectations. Intraday readings are approximate and drawn from the sources cited.
Earnings-day move
Versus the prior close
Early reading per Yahoo Finance. Close per StockAnalysis, $433.74. Bar scale is 0% to 6%.
52-week range
Humana share price, $
Range $163.11 to $456.50. The close sat about 92% of the way from the low to the high.
Star Ratings: near a record, and a one-time 2028 tailwind
Humana's 2027 Star Ratings, announced Oct 9, 2026, put 95% of its Medicare Advantage members in plans rated 4.0 Stars or higher and 42% in 4.5-Star plans, against 20% in 4.0-plus-Star plans for 2026. On the Q3 call management tied this result to what it calls bonus year 2028, reporting a member-weighted Star rating of 4.17 and saying the result significantly exceeds its top quartile goal, the level it says it needs to sustain a 3% margin. It will keep managing benefits and costs to a top quartile level, so the surplus becomes a one-time 2028 tailwind: some invested in Stars capability, customer experience and clinical outcomes, and some returned to shareholders, with sizing to come as 2028 competition, membership and regulation become clearer. For bonus year 2029, Humana is running about 5% ahead of last year's quality improvement rate on key HEDIS measures and expects top quartile again.
Medicare Advantage: margin first for 2027, with membership still expected to grow
Humana said its number one priority in 2027 bids was to price for margin, with retention second and growth a distant third, and that its portfolio puts it on track for a 3%-plus margin in 2028. AEP is ahead of initial expectations, recapture of members from exited plans is strong and new sales are ahead of plan, so membership is now expected to be up for 2027, though not by as much as in 2026. Individual Medicare Advantage membership reached 6.46 million at Sep 30, up 23% from year end, and D-SNP membership rose 25% to 958,300 from 765,800 a year earlier. Management will update its 2028 commitments at an investor event on Dec 10.
The 2027 map: 861 plans, down from 887
Humana goes from 887 Medicare Advantage plans to 861, a drop of 26, against an all-payer net decline of 34 plans (5,592 to 5,558), and it enters 4 counties and exits 61. Florida plans go from 121 to 122, Texas from 71 to 72 and Virginia from 45 to 49. Special needs plans are 240 of 861, or 27.9%, with 137 D-SNP, 86 C-SNP and 17 I-SNP plans. On drug deductibles, 37 plans keep a $0 deductible, and plans in the top tier rise to 504 at $700 from 472 at $615 in 2026. Counts come from HealthWorksAI's analysis of the CMS 2027 plan benefit and crosswalk files.
Plans in the three largest states
Humana Medicare Advantage plans, 2026 to 2027
20262027
Florida 121 to 122, Texas 71 to 72, Virginia 45 to 49. Scale 0 to 130 plans.
Total plans
Humana Medicare Advantage plans, 2026 to 2027
−26 plans, while all payers together fall by a net 34, from 5,592 to 5,558.
Counties entered and exited
4 entered and 61 exited, a net loss of 57
Humana entered 4 counties and exited 61. A county counts as exited only when Humana has no plan left in it.
Special needs plans, share of 2027 plans
Humana 240 of 861 plans, against 35% for all payers
Humana, 27.9%
All payers, 35%
Plans with a $0 drug deductible
Humana 37 of 861 plans in 2027, against 450 of 5,558 for all payers
Humana, 4.3%
All payers, 8.1%
Top drug deductible tier, Humana plans
The tier moved from $615 in 2026 to $700 in 2027
+32 plans, from 53.2% of plans to 58.5%. A higher tier count says little about member costs on its own.
True Plan Value™ slips for 2027 as Part D rises
HealthWorksAI TPV™ (True Plan Value) is a proprietary measure of the value of plan benefits members realize above and beyond traditional Medicare, across Part C, Part D and Part B giveback. Humana's relative average falls from $534.7 in 2024 to $479.3 in 2025, rises to $501.5 in 2026, then slips to $496.9 in 2027, a decline of 0.9% that leaves it 3.7% above 2025 and about 7% below 2024. The top 20 payers by total plan count average $494 for 2027, up from $485 for 2026, so Humana sits about 0.6% above them for 2027, against about 3.4% above them for 2026.
By category, Part D is the largest component of Humana's relative TPV, at about 57% of the value in 2027, up from about 54% in 2026. Part D rose from $273.2 to $284.2, while supplemental benefits fell from $69.8 to $62.8, Original Medicare value add fell by $6.0 and Part B giveback by $2.6.
Humana relative TPV™ by key benefit category
Average relative TPV by category, $ per member per month, 2026 and 2027, with the change in $
Supplemental Benefit Value Add−$7.0
Original Medicare Value Add−$6.0
Part D+$11.0
Part B giveback−$2.6
Bar scale is $0 to $400. Top 20 payers by total plan count: $485 in 2026 and $494 in 2027.
In Humana's three largest states by plan count, Part D is the largest category in 2027 in Florida ($307.4) and Virginia ($308.4), against $25.1 in Texas, both above Humana's overall Part D average of $284.2. Florida is highest on supplemental benefits ($88.9) and giveback ($45.8), and Texas on Original Medicare value add ($166.1), just above Florida's $164.9.
Florida
Average relative TPV by category, 2027, $ per member per month
Supplemental Benefit Value Add
Original Medicare Value Add
Part D
Part B giveback
Texas
Average relative TPV by category, 2027, $ per member per month
Supplemental Benefit Value Add
Original Medicare Value Add
Part D
Part B giveback
Virginia
Average relative TPV by category, 2027, $ per member per month
Supplemental Benefit Value Add
Original Medicare Value Add
Part D
Part B giveback
Average relative TPV by category, $ per member per month, 2027, for Florida, Texas and Virginia, Humana's three largest states by 2027 plan count. Bar scale is $0 to $400.
Humana said its 2027 portfolio protects the benefits and services seniors identify as most important, and its relative plan value is nearly flat. Underneath, value moves toward Part D, where Humana expects 14% to 15% cost trend, while supplemental benefits, Original Medicare value add and giveback all thin and more plans sit in the top drug deductible tier. Averages blend plan and county mix, so the 26 fewer plans and 61 county exits can also move the average.
Humana relative average True Plan Value™
Relative average across Humana plans, 2024 to 2027
Year-over-year change in True Plan Value™
Relative average
Bar scale is 0% to 10.4% in size. Top 20 payers by total plan count, $485 to $494 (2027 shown). Averages blend plan and county mix, so read the direction more than the decimals.
From the HealthWorksAI desk · The 2028 bid
Humana trimmed its map and moved value into Part D. Both were bid decisions.
861 plans against 887, 61 counties exited and 4 entered, 504 plans in the $700 deductible tier against 472 a year ago, and True Plan Value™ down 0.9% to $496.9, against $494 for the top 20 payers. Humana priced for margin first and retention second, and says AEP is running ahead of its initial expectations with near-record Stars behind its product. The question for 2028 is which of Humana's members your plans can win, including those in its 61 exited counties and those weighing thinner supplemental benefits, and which benefits would do it. That can be modeled, benefit by benefit, before anything is filed.
How plans test a benefit change before they bid →Section 5
Where the guidance goes from here
2026 adjusted EPS guide
$ per share, at least
The guide is a floor, not a range. 2025 adjusted EPS was $17.14. Bar scale is $0 to $10.
2026 GAAP EPS guide
$ per share, at least
The Q3 jump reflects non-cash valuation changes tied to the CenterWell joint ventures. Bar scale is $0 to $16.
Cost trend, priced into 2027 bids
Annual trend, %, top of each range
2026 trend is running at the lower end of 7% to 8%. Bars show the top of each range. Bar scale is 0% to 16%.
Section 6
How the competitive picture is shifting
Humana is trimming plans and counties at once
It goes from 887 plans to 861 and exits 61 counties while entering 4, against an all-payer net decline of 34 plans (5,592 to 5,558).
The larger players expect to gain from exits
Management says the large players look better positioned than expected for AEP, given plan exits across most of them and some consolidation of smaller plans.
Part D is the 2027 cost pressure point
Humana prices 2027 Part D trend at 14% to 15%, up from 11% to 12%, driven by the health technology pipeline, and its Part D value rises as supplemental benefits thin.
The market rewarded the raise
Shares closed up 5.33% at $433.74 after an early dip of about 0.8%, near the top of a 52-week range of $163.11 to $456.50.
Beyond the quarter: Humana signals from the call
Debt-to-total capitalization
%
Down 180 bps on commercial paper repayment. The BlackRock joint venture should cut about 130 bps more in Q4. Bar scale is 0% to 45%.
CenterWell segment, Q3
$ million
Primary care patients grew by 146,800, or 30%, this year. Bar scale is $0 to $7,157M.
Section 7
What this means for your plan
If you compete with Humana in Medicare Advantage
Humana exits 61 counties and enters 4, so members in exited counties must choose a new plan this AEP. It adds four plans in Virginia and one each in Florida and Texas, and says recapture of members from exited plans is strong.
If you compete for dual eligible members
Humana's D-SNP membership rose 25% to 958,300 from 765,800 a year earlier, it files 137 D-SNP plans for 2027, and its Medicaid footprint spans 13 states, with integrated duals programs in Michigan, Illinois and South Carolina.
If you compete for Part D members
Humana's Part D value rises to $284.2, about 57% of its plan value, with 504 plans in the $700 deductible tier and 37 at $0. It reported 4.03 million stand-alone PDP members and prices 2027 Part D trend at 14% to 15%.
If you benchmark Star Ratings
Humana's 2027 Star Ratings put 95% of members in plans rated 4.0 Stars or higher, which management tied to a member-weighted 4.17 Stars for what it calls bonus year 2028, and it plans its benefits and costs around a top quartile level rather than this result.
Reading note: HealthWorksAI's enrollment count of 6,448,146 individual Medicare Advantage members in Sep 2026 and Humana's reported individual Medicare Advantage membership of 6,456,900 at Sep 30, 2026 use different bases, so the two figures differ slightly.
How HealthWorksAI helps you act on this
HealthWorksAI brings payer moves by county, benefit value by plan and network fit into one platform, so a plan team can see where a competitor's 2027 map overlaps its own markets.
Your next move
From what changed in 2027 to what your team does about it
The 2028 bid, this AEP's enrollment and next year's network plan all start from these shifts. Here is where each team picks them up.
Common questions
Humana Q3 2026 earnings: common questions
What were Humana's Q3 2026 results?
Humana reported an adjusted loss of $0.70 per share for Q3 2026, against about a $1.00 loss expected (Yahoo Finance; Zacks shows $1.03), and GAAP EPS of $1.33. Revenue rose 26% to $41.2 billion, against $40.87 billion expected. The Insurance segment benefit ratio was 93.7%, better than management's guide of slightly above 94% and up from 91.1% a year earlier.
Did Humana change its 2026 guidance?
Yes. Adjusted EPS is now expected to be at least $9.50, up from at least $9.00 and above the $9.16 consensus, and GAAP EPS at least $15.09, up from at least $6.52, mostly on non-cash valuation changes tied to its CenterWell joint ventures. Revenue of at least $160 billion, an Insurance segment benefit ratio of 92.75% plus or minus 25 basis points and individual Medicare Advantage growth of about 25% were left unchanged.
How did Humana's stock react to Q3 2026 earnings?
Yahoo Finance reported shares down about 0.8% after the release on Nov 6, 2026. By the close, Humana was up 5.33% at $433.74 from a $411.79 prior close, after an intraday high of $444.00, within a 52-week range of $163.11 to $456.50. Intraday readings are approximate.
What did Humana say about its Star Ratings?
Humana's 2027 Star Ratings, announced Oct 9, 2026, put 95% of its Medicare Advantage members in plans rated 4.0 Stars or higher, against 20% for 2026. On the Q3 call management tied this to what it calls bonus year 2028, reporting a member-weighted Star rating of 4.17, which it said approaches the highest it has achieved. Because it manages the business to a top quartile level, it expects a one-time 2028 tailwind, part reinvested and part returned to shareholders.
What did Humana say about 2027?
Humana priced 2027 bids for margin first, retention second and growth a distant third. It expects material improvement in individual Medicare Advantage margin, membership to be up for 2027 and cost trend of 8% to 9%, with Part D at 14% to 15%. It will update its 2028 commitments at an investor event on Dec 10.
What is Humana's True Plan Value™ for 2027?
HealthWorksAI's True Plan Value™, a proprietary measure of benefit value, averages $496.9 on a relative basis across Humana's 861 Medicare Advantage plans for 2027, against $501.5 for 2026, a 0.9% decrease. The top 20 payers by total plan count average $494, up from $485. Part D is Humana's largest component at $284.2, while supplemental benefit value fell $7.0 to $62.8.
How many Medicare Advantage plans will Humana offer in 2027?
HealthWorksAI's analysis of CMS data shows 861 Humana Medicare Advantage plans for 2027 against 887 in 2026, with 4 counties entered and 61 exited. Florida has 122 plans, Texas 72 and Virginia 49.
How many Medicare Advantage members does Humana have?
Humana reported 6,456,900 individual Medicare Advantage members and 728,300 group Medicare Advantage members at Sep 30, 2026, with individual membership up 23% from year end. HealthWorksAI's enrollment data shows 6,448,146 individual Medicare Advantage members in Sep 2026, on a different basis.
What are Humana's drug deductibles for 2027?
HealthWorksAI's analysis of CMS data shows 37 of Humana's 861 Medicare Advantage plans have a $0 drug deductible for 2027. Plans in the top deductible tier go from 472 at $615 in 2026 to 504 at $700 in 2027, which is 58.5% of the 2027 book against 53.2% in 2026.